Daily Fundamental Analysis October 26 2026 | FastPip
Daily Fundamental Analysis October 26 2026: 7 Critical Market Drivers
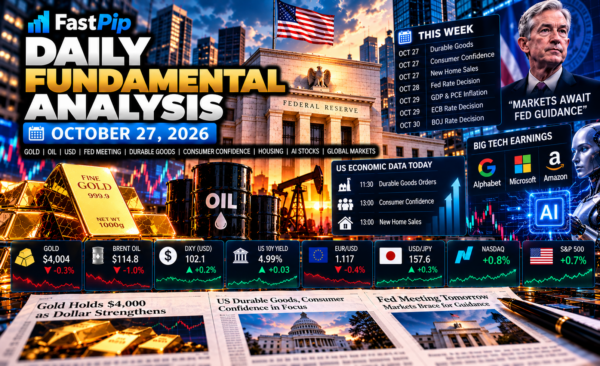
The Daily Fundamental Analysis October 26 2026 begins with gold attempting to stabilize around the psychologically important $4,000 region, crude oil retreating from six-month highs, Treasury yields holding below 5%, and investors preparing for one of the most important central-bank weeks of the quarter.
Gold traded around the $4,000 area during Monday’s Asian and European sessions after last week’s steep decline.
Oil moved lower after diplomatic efforts raised hopes that tensions involving the United States and Iran could ease.
Brent crude fell toward $114 per barrel, after settling at almost $117 on Friday.
The US Dollar Index also softened toward 101.6, while the US 10-year Treasury yield remained around 4.97%.
Markets are now entering a major event cluster.
The Federal Reserve announces its policy decision on Wednesday.
The European Central Bank and Bank of Japan also meet this week.
US GDP, PCE inflation, Durable Goods Orders, Consumer Confidence and New Home Sales are all scheduled over the coming days.
At the same time, investors will receive earnings from some of the world’s largest technology companies, including Alphabet, Microsoft and Amazon.
Today’s seven major market drivers are:
- Gold stabilizing around $4,000
- Oil retreating from six-month highs
- The Federal Reserve meeting on Wednesday
- US Treasury yields below 5%
- German Ifo Business Climate
- AI and Big Tech earnings
- A heavy US macroeconomic calendar later this week
For live data releases throughout the week, traders can follow the FastPip Economic Calendar.
Daily Fundamental Analysis October 26 2026: Global Market Snapshot
| Asset / Market | Latest Reported Level / Move | Fundamental Signal |
|---|---|---|
| Gold / XAUUSD | Around $4,000 | Neutral → Mildly Bullish |
| Brent Oil | ~$114.2–$114.5 | Lower |
| WTI Oil | ~$100.9 | Lower |
| DXY | ~101.64 | Mildly Bearish |
| US 10Y Yield | ~4.97% | Below 5% |
| EUR/USD | ~1.122 | Mildly Bullish |
| GBP/USD | ~1.3385 | Mildly Bullish |
| USD/JPY | ~156.9 | Neutral |
| Nikkei 225 | ~-0.2% | Cautious |
| South Korea Equities | ~-0.5% | Cautious |
| China Blue Chips | ~-0.5% | Bearish |
Monday’s global session began cautiously as investors weighed lower oil prices against central-bank risk, inflation concerns and another major technology earnings week.
Read the latest Reuters global-markets report.
Gold Fundamental Analysis Today
Gold is attempting to stabilize after last week’s heavy selloff.
The metal traded around the $4,000 region during Monday’s session.
This area has become one of the most important psychological and technical zones for XAUUSD.
Gold lost significant ground last week because the surge in oil prices increased inflation expectations and strengthened the case for higher-for-longer US interest rates.
Today, that pressure has eased slightly.
Oil prices are lower.
Treasury yields remain below 5%.
The US dollar is softer.
Together, these factors create a more constructive environment for bullion.
Why Lower Oil Helps Gold
The key relationship is:
Oil ↓ → Inflation Expectations ↓ → Fed Pressure ↓ → Treasury Yield Pressure ↓ → Gold Support
This does not mean gold automatically rises whenever oil falls.
However, energy prices have become one of the largest inflation risks facing the Federal Reserve.
Therefore, a sustained decline in crude could materially improve gold’s fundamental setup.
Gold Bullish Drivers
Gold is currently supported by:
- softer oil prices;
- Treasury yields below 5%;
- weaker US dollar momentum;
- geopolitical uncertainty;
- central-bank policy risk;
- potential AI-sector volatility;
- global fiscal concerns.
Gold Bearish Drivers
The main risks remain:
- persistent inflation;
- a potential December Fed rate hike;
- renewed oil strength;
- Treasury yields moving back above 5%;
- stronger US macro data later this week.
Gold Bullish Scenario
Gold could recover more convincingly if:
- Brent falls below $112;
- the US 10-year yield remains under 5%;
- DXY breaks lower;
- the Fed signals patience;
- PCE inflation is softer than expected.
Potential reaction:
Gold ↑
EUR/USD ↑
Treasuries ↑
DXY ↓
Gold Bearish Scenario
Gold could weaken again if:
- Brent returns toward $118–120;
- Treasury yields break back above 5%;
- Fed guidance is hawkish;
- PCE inflation exceeds expectations;
- GDP remains exceptionally strong.
Potential reaction:
Gold ↓
DXY ↑
USD/JPY ↑
Gold Fundamental Bias
Neutral to Mildly Bullish
The $4,000 region remains critical.
The short-term environment has improved because both oil and Treasury yields have eased, but the Federal Reserve meeting prevents a stronger bullish bias.
Traders can compare this macro setup with current FastPip Trading Signals.
Oil Fundamental Analysis Today
Oil prices declined on Monday after last week’s powerful rally.
Brent fell roughly 2% toward $114 per barrel.
WTI moved toward approximately $101.
The decline followed reports that Qatari mediators were travelling to Tehran as part of efforts to reduce tensions between the United States and Iran.
Reuters reported that Brent fell after closing Friday at $116.72, while WTI had settled at $103.27.
Read the Reuters oil-market report.
Why Oil Is Falling Today
Markets are reducing part of the geopolitical risk premium.
The main reasons are:
- renewed diplomatic efforts;
- hopes for lower US-Iran tensions;
- profit-taking after last week’s rally;
- concerns about demand destruction at extremely high prices.
However, the geopolitical situation remains fragile.
Saudi infrastructure has experienced repeated attacks.
The Strait of Hormuz and regional shipping routes also remain major sources of supply risk.
Oil Bullish Drivers
- Saudi infrastructure risk;
- Houthi attacks;
- Strait of Hormuz disruption;
- physical supply constraints;
- high insurance and freight costs.
Oil Bearish Drivers
- diplomatic de-escalation;
- potential supply normalization;
- strategic reserve releases;
- demand destruction above $110;
- slowing global growth.
Oil Fundamental Bias
Neutral to Mildly Bearish Intraday
The immediate direction is lower, but the broader geopolitical environment remains highly volatile.
The Federal Reserve Meeting Is the Main Event This Week
The Federal Reserve meets on October 27–28.
The policy decision is expected on Wednesday.
A Reuters poll shows that 94 of 100 economists expect the Federal Reserve to leave rates unchanged at the October meeting.
However, all economists in that poll expect another rate increase in December.
Read the Reuters Federal Reserve poll.
This distinction is extremely important.
The market’s current base case is:
October: Hold
but:
December: Hike
That means the statement and Chair Kevin Warsh’s press conference may matter more than the rate decision itself.
Fed Scenario Analysis
Scenario 1: Hawkish Hold
The Fed leaves rates unchanged but emphasizes:
- persistent inflation;
- strong economic activity;
- energy-price pressure;
- resilient labor markets.
Potential reaction:
Treasury Yields ↑
DXY ↑
Gold ↓
Nasdaq ↓
This would strengthen expectations for a December hike.
Scenario 2: Neutral Hold
The Fed keeps rates unchanged without materially changing forward guidance.
Markets would likely move quickly toward Thursday’s GDP and PCE data.
Gold could remain range-bound around the $4,000 region.
Scenario 3: Dovish Hold
The Fed emphasizes:
- housing weakness;
- financial-market stress;
- softer hiring;
- tighter financial conditions.
Potential reaction:
Treasury Yields ↓
DXY ↓
Gold ↑
Nasdaq ↑
This would be the most constructive scenario for gold.
US Treasury Yields Remain Below 5%
The 10-year Treasury yield traded around 4.97% on Monday.
The 30-year yield was near 5.30%.
These levels remain extremely important for gold and technology stocks.
For gold:
Treasury Yields ↓ = Lower Opportunity Cost
For technology:
Treasury Yields ↓ = Higher Valuation Support
For the dollar:
Treasury Yields ↓ = Less Yield Advantage
This explains why DXY is softer today despite persistent US inflation.
US Dollar Fundamental Analysis
The US dollar started the week slightly weaker.
The Dollar Index traded around 101.64.
EUR/USD moved toward approximately 1.122.
GBP/USD traded near 1.3385.
Reuters reported that falling Treasury yields and softer oil prices reduced support for the US currency as investors prepared for a week packed with central-bank decisions.
Read the Reuters currency-market report.
US Dollar Bullish Drivers
- persistent inflation;
- December Fed-hike expectations;
- strong US economic growth;
- relatively high interest rates.
US Dollar Bearish Drivers
- falling Treasury yields;
- lower oil prices;
- Fed expected to hold this week;
- safe-haven demand shifting into Treasuries and yen.
US Dollar Fundamental Bias
Neutral to Mildly Bearish
The next major directional catalyst is the Federal Reserve.
EUR/USD Fundamental Analysis
EUR/USD is benefiting from a softer dollar.
However, Europe continues to face weak growth and fiscal risks.
Germany’s Ifo Business Climate report is therefore particularly important today.
EUR/USD Bullish Scenario
EUR/USD could extend higher if:
- German Ifo beats expectations;
- US yields decline;
- DXY weakens;
- Fed guidance is less hawkish.
EUR/USD Bearish Scenario
The pair could fall if:
- German confidence disappoints;
- Treasury yields rise;
- the Fed strengthens December tightening expectations.
EUR/USD Fundamental Bias
Neutral
The pair has short-term USD support but still faces weak European fundamentals.
German Ifo Business Climate
Germany’s October Ifo Business Climate Index is scheduled for 09:00 GMT.
The consensus is approximately 90.0, compared with 89.9 previously.
The index measures business sentiment across manufacturing, services, trade and construction.
The official survey is produced by the ifo Institute.
German Ifo Data
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Ifo Business Climate | Pending | 90.0 | 89.9 |
| Business Expectations | Pending | — | 90.4 |
A reading above expectations would provide some evidence that Europe’s largest economy is stabilizing.
A weaker result would reinforce concerns about Eurozone growth.
German Ifo Scenario Analysis
Above 90.0
Potential reaction:
EUR ↑
European Equities ↑
EUR/USD Support
Below 89.9
Potential reaction:
EUR ↓
German Yields ↓
European Growth Concerns ↑
Japan Leading Index Confirms Stronger Outlook
Japan’s final August Leading Economic Index was confirmed at 118.0.
That matches the preliminary estimate and represents the strongest level in more than 12 years.
The improvement reflects stronger fiscal support and relatively resilient labor-market conditions.
However, Japanese inflation also remains elevated.
This creates a more complicated Bank of Japan outlook.
USD/JPY Fundamental Analysis
USD/JPY traded around 156.9.
The yen continues to receive some safe-haven demand ahead of the Bank of Japan meeting later this week.
US yields below 5% also reduce the attractiveness of long-dollar carry trades.
USD/JPY Bullish Drivers
- wide US-Japan rate differential;
- possible December Fed hike;
- resilient US growth.
USD/JPY Bearish Drivers
- stronger Japanese inflation;
- potential BOJ tightening;
- lower US yields;
- global risk aversion.
USD/JPY Fundamental Bias
Neutral to Mildly Bearish
The BOJ meeting could become the next major catalyst.
A Major Central-Bank Week
This week includes policy decisions from several major central banks.
The most important include:
- Federal Reserve
- European Central Bank
- Bank of Japan
- Bank of Canada
- Reserve Bank of New Zealand
The Fed, ECB and BOJ are broadly expected to keep rates unchanged.
The Bank of Canada and Reserve Bank of New Zealand have more uncertain policy outlooks.
This makes forward guidance extremely important.
AI and Big Tech Earnings Return to Focus
The global technology sector faces another critical test this week.
Major earnings include:
- Alphabet;
- Microsoft;
- Amazon;
- Intel;
- major Asian semiconductor companies.
Investors are no longer focused only on AI revenue growth.
The main questions are increasingly:
How much capital expenditure is required?
How much debt is being used?
What return is companies’ AI spending producing?
This is particularly important after the recent technology selloff drove investors into Treasury securities.
Nasdaq Fundamental Outlook
Lower Treasury yields provide immediate support for technology valuations.
However, the Nasdaq remains vulnerable to earnings disappointment.
Nasdaq Bullish Scenario
The strongest bullish combination would be:
Strong Earnings + Controlled AI Spending + Yields Below 5%
Potential reaction:
Nasdaq ↑
Semiconductors ↑
Risk Appetite ↑
Nasdaq Bearish Scenario
The biggest risk is:
Higher AI Spending + Weak Cash Flow + Higher Yields
Potential reaction:
Nasdaq ↓
Treasury Safe-Haven Demand ↑
Nasdaq Fundamental Bias
Neutral / High Volatility
This week’s earnings could determine whether the recent AI correction stabilizes.
S&P 500 Fundamental Outlook
The S&P 500 also enters a major earnings week.
Strong corporate profitability remains one of the market’s biggest supports.
However, investors must balance earnings strength against:
- expensive valuations;
- persistent inflation;
- high energy costs;
- Fed uncertainty.
S&P 500 Fundamental Bias
Neutral to Mildly Bullish
Lower Treasury yields are supportive, but the Fed remains a major event risk.
Today’s Key Economic Events — October 26, 2026
The Daily Fundamental Analysis October 26 2026 focuses on a relatively light Monday calendar before much larger releases later in the week.
All times below are shown in GMT / UTC.
| Time GMT | Currency | Event | Actual | Forecast | Previous |
|---|---|---|---|---|---|
| 05:00 | JPY | Leading Index Final | 118.0 | 118.0 | 118.0 |
| 09:00 | EUR | Germany Ifo Business Climate | Pending | 90.0 | 89.9 |
| 12:30 | USD | Chicago Fed National Activity Index | Pending | Around -0.1 | -0.04 |
| 14:30 | USD | Dallas Fed Manufacturing Index | Pending | Around 7.0 | 9.8 |
| 15:30 | USD | 3-Month Bill Auction | Pending | — | 4.095% |
| 15:30 | USD | 6-Month Bill Auction | Pending | — | 4.220% |
| 17:00 | USD | 2-Year Note Auction | Pending | — | 4.787% |
Consensus estimates can vary slightly between economic-calendar providers.
The official Chicago Fed release calendar confirms today’s CFNAI publication.
For actual values after release, use the FastPip Economic Calendar.
Chicago Fed National Activity Index
The Chicago Fed National Activity Index is today’s main US macro release.
The previous reading was -0.04.
A negative figure indicates economic activity is running slightly below its historical trend.
Stronger CFNAI Scenario
If the index moves clearly above expectations:
US Growth Expectations ↑
Treasury Yields ↑
USD ↑
Gold ↓
Weaker CFNAI Scenario
If the indicator deteriorates:
Growth Concerns ↑
Treasury Yields ↓
Gold ↑
However, today’s release is unlikely to overshadow Wednesday’s Federal Reserve decision.
Dallas Fed Manufacturing Survey
The Dallas Fed Manufacturing Index is also due later today.
Consensus estimates center near 7, compared with approximately 9.8 previously.
A weaker reading would suggest some moderation in regional manufacturing conditions.
A stronger result could support the dollar modestly but is unlikely to dominate global markets.
Tomorrow’s US Data: The Calendar Gets Much Heavier
Tuesday brings several important releases.
Durable Goods Orders
September Durable Goods Orders are expected to increase approximately 0.6%, compared with roughly flat activity previously.
Orders excluding transportation are also expected to increase around 0.6%.
Consumer Confidence
US Consumer Confidence is expected near 80.5, compared with 81.9 previously.
New Home Sales
New Home Sales are expected around 660,000 annualized units, compared with approximately 680,000 previously.
These reports will help establish the macro backdrop immediately before the Fed decision.
Thursday: GDP and PCE Become Critical
Thursday could ultimately be the biggest macroeconomic session of the week.
The United States is scheduled to publish:
- Q3 GDP;
- Personal Income;
- Personal Spending;
- PCE Inflation;
- Core PCE Inflation;
- Initial Jobless Claims.
Current forecasts suggest US annualized Q3 growth near 3.2%.
Core inflation remains the most important number for Fed expectations.
The US Bureau of Economic Analysis publishes GDP and PCE data.
Why PCE Matters
PCE is the Federal Reserve’s preferred inflation measure.
A stronger core PCE print after Wednesday’s Fed meeting could strengthen expectations for a December hike.
A softer reading could challenge that assumption.
Daily Fundamental Analysis October 26 2026: Market Bias
| Asset | Fundamental Bias | Confidence | Main Driver |
|---|---|---|---|
| Gold / XAUUSD | Neutral → Mildly Bullish | Moderate | Lower oil + yields |
| Silver / XAGUSD | Neutral | Low | Gold direction |
| DXY | Neutral → Bearish | Moderate | Lower yields |
| EUR/USD | Neutral → Bullish | Moderate | Softer USD |
| GBP/USD | Neutral → Bullish | Low | USD weakness |
| USD/JPY | Neutral → Bearish | Moderate | Lower yields + BOJ |
| S&P 500 | Neutral → Bullish | Moderate | Earnings + lower yields |
| Nasdaq | Neutral / Volatile | High | AI earnings |
| Brent Oil | Neutral → Bearish | Moderate | De-escalation hopes |
| WTI Oil | Neutral → Bearish | Moderate | De-escalation hopes |
| US Treasuries | Mildly Bullish | Moderate | Fed caution + risk demand |
7 Trader Watchpoints for October 26, 2026
1. Gold Around $4,000
This remains the most important short-term level for bullion.
A sustained recovery above $4,000 would improve sentiment significantly.
2. Brent Near $114
Oil has pulled back but remains historically high.
A renewed move toward $117–120 would revive inflation concerns immediately.
3. US 10-Year Yield Below 5%
This is one of today’s most important cross-asset signals.
As long as yields remain below 5%, gold and technology stocks receive some support.
4. German Ifo Business Climate
A reading above 90 could provide modest support for EUR/USD.
5. Federal Reserve Expectations
Markets expect a hold on Wednesday.
The real question is whether the Fed confirms or challenges expectations for a December hike.
6. Big Tech Earnings
Alphabet, Microsoft and Amazon will help determine whether AI-related investment concerns continue.
7. Thursday’s GDP and PCE Data
These releases could materially change December Fed pricing.
Combined Scenario Analysis
Scenario 1: Oil Continues Falling + Treasury Yields Stay Below 5%
This is the most constructive setup for gold.
Potential reaction:
Gold ↑
DXY ↓
Nasdaq ↑
EUR/USD ↑
Scenario 2: Oil Returns Above $118
This would revive the inflation shock.
Potential reaction:
Inflation Expectations ↑
Fed-Hike Risk ↑
Gold ↓
Nasdaq ↓
Scenario 3: Hawkish Fed + Strong GDP
This would be strongly supportive for the dollar.
Potential reaction:
Treasury Yields ↑
DXY ↑
Gold ↓
USD/JPY ↑
Scenario 4: Dovish Fed + Soft PCE
This would be the strongest bullish macro scenario for gold.
Potential reaction:
Treasury Yields ↓
DXY ↓
Gold ↑
Nasdaq ↑
Scenario 5: Weak AI Earnings
If major technology companies disappoint:
Nasdaq ↓
Treasasury Demand ↑
Yields ↓
Gold could eventually benefit from the decline in yields and increased financial-market uncertainty.
Final Daily Fundamental Outlook
The Daily Fundamental Analysis October 26 2026 shows global markets entering one of the most important weeks of the month.
Gold is attempting to stabilize around $4,000.
Oil is retreating from six-month highs.
Treasury yields remain below 5%.
The US dollar is softer.
These developments provide some relief after last week’s inflation-driven market pressure.
However, the improvement remains fragile.
Oil is still above $110.
Inflation remains elevated.
The Federal Reserve is still expected to raise rates again later this year.
The key question is no longer whether the Fed changes rates on Wednesday.
The key question is:
How strongly does the Fed signal a December hike?
For gold, the strongest bullish setup is:
Oil ↓ + Treasury Yields Below 5% + Dovish Fed Guidance
The strongest bearish setup is:
Oil ↑ + Hawkish Fed + Strong PCE
For the dollar:
Treasury Yields + Fed Guidance
For Nasdaq:
AI Earnings + Treasury Yields
For EUR/USD:
German Data + Fed Direction
The central market question today is:
Can easing oil prices and lower Treasury yields allow gold to rebuild support above $4,000 before the Federal Reserve decision?
The answer could determine the next major directional move across precious metals, forex and global equity indices.
For definitions of Treasury yields, Federal Reserve policy, inflation and other concepts used in this analysis, visit the FastPip Financial Glossary.
Frequently Asked Questions
What Is the Daily Fundamental Analysis October 26 2026 Outlook for Gold?
The Daily Fundamental Analysis October 26 2026 suggests a neutral-to-mildly bullish short-term outlook for gold as oil prices and Treasury yields decline.
The $4,000 region remains the most important support zone.
Why Is Gold Stabilizing Today?
Gold is benefiting from lower crude oil prices, Treasury yields below 5% and a slightly weaker US dollar.
Why Is Oil Falling Today?
Oil is retreating as diplomatic efforts increase hopes that US-Iran tensions could ease after last week’s sharp geopolitical rally.
What Is Brent Crude Trading Near?
Brent traded around $114 per barrel during Monday’s session after closing near $116.72 on Friday.
Is the Federal Reserve Expected to Raise Rates This Week?
Most economists expect the Federal Reserve to hold rates unchanged at the October 27–28 meeting.
However, expectations for a December rate increase remain high.
What Is the Main US Economic Release Today?
The Chicago Fed National Activity Index is the main scheduled US macro release today.
What Is the German Ifo Forecast?
Germany’s Ifo Business Climate is expected around 90.0, compared with 89.9 previously.
Is the US Dollar Bullish Today?
The dollar has a neutral-to-mildly bearish fundamental bias because lower Treasury yields and softer oil are limiting demand for the currency.
What Is the Biggest Market Event This Week?
The Federal Reserve decision on Wednesday, October 28 is the most important scheduled event, followed by US GDP and PCE inflation on Thursday.
What Should Traders Watch After the Daily Fundamental Analysis October 26 2026?
Following the Daily Fundamental Analysis October 26 2026, traders should monitor gold around $4,000, Brent crude near $114, the US 10-year Treasury yield below 5%, German Ifo data, the Federal Reserve meeting, Big Tech earnings, Thursday’s US GDP and PCE inflation, and the US Dollar Index.
 Check Our
 Whether you’re a day trader or a long-term investor, FastPip gives you the tools to trade smarter, not harder.