Daily Fundamental Analysis November 9 2026 | FastPip
Daily Fundamental Analysis November 9 2026: 7 Critical Market Risks
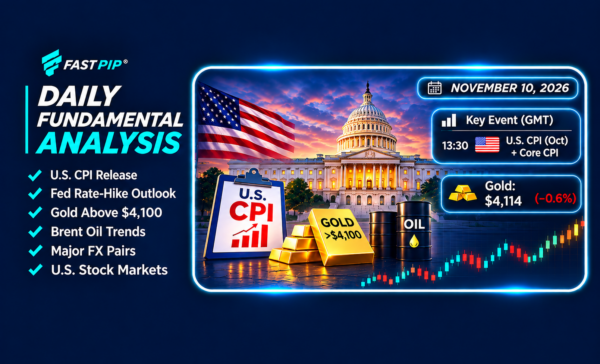
The Daily Fundamental Analysis November 9 2026 begins with gold extending last week’s powerful recovery, crude oil remaining below $100, the US dollar holding firm after Friday’s strong employment report, and global technology markets attempting to stabilize after one of their most volatile weeks of the year.
Spot gold climbed approximately 1.4% to $4,123.46 per ounce, while December gold futures rose to around $4,132.70.
The metal gained roughly 5% last week and is receiving fresh support from softer crude-oil prices, which reduce some of the inflation pressure that had weighed heavily on bullion during October.
Brent crude traded around $98.35 per barrel, while WTI held near $91.30.
Meanwhile, the US Dollar Index remained firm near 102.2 after Friday’s Nonfarm Payrolls report showed the US economy added 165,000 jobs in October and unemployment declined to 4.1%.
Markets now assign roughly an 80%–81% probability of another Federal Reserve rate hike in December.
Today’s seven major market drivers are:
- Gold rising above $4,120
- Brent crude remaining below $100
- December Fed-hike probability near 80%
- US CPI due Tuesday
- Dollar Index around 102.2
- China producer inflation surging to 5.7%
- AI stocks attempting to stabilize after last week’s correction
For live macro releases and upcoming events, traders can monitor the FastPip Economic Calendar.
Daily Fundamental Analysis November 9 2026: Global Market Snapshot
| Asset / Market | Latest Reported Level / Move | Fundamental Signal |
|---|---|---|
| Gold / XAUUSD | ~$4,123 | Bullish |
| Silver / XAGUSD | ~$53.15 | Bullish |
| Brent Oil | ~$98.35 | Neutral → Bearish |
| WTI Oil | ~$91.30 | Neutral → Bearish |
| DXY | ~102.2 | Mildly Bullish |
| EUR/USD | ~1.1148 | Neutral → Bearish |
| USD/JPY | ~158.22 | Mildly Bullish |
| Asia ex-Japan | +2.0% | Risk-On Rebound |
| Nikkei 225 | +3.5% | Bullish |
| Korean Equities | +1.8% | Recovery |
| S&P 500 Futures | +0.6% | Mildly Bullish |
The immediate market structure is unusually supportive for gold:
Oil ↓ → Inflation Pressure ↓
while:
AI Risk + Political Uncertainty → Safe-Haven Demand
However:
Strong NFP → Fed-Hike Expectations ↑
That prevents the gold outlook from becoming fully bullish.
Gold Fundamental Analysis Today
Gold is one of the strongest-performing major assets at the start of the week.
Spot bullion rose approximately 1.4% to $4,123.46 per ounce, extending last week’s roughly 5% gain.
The latest move is being driven primarily by lower oil prices and a softer dollar during parts of Monday’s session.
Reuters reported that lower energy prices are helping reduce the inflation concerns that had previously weighed on gold.
Read the latest Reuters gold-market report.
Why Lower Oil Is Bullish for Gold
Oil has become one of the most important inflation variables in 2026.
The transmission mechanism is:
Oil ↓
→ Inflation Expectations ↓
→ Fed Tightening Pressure ↓
→ Real Yield Pressure ↓
→ Gold Support ↑
Brent remains below $100 after losing approximately 16% last week.
That is a dramatic change from late October, when Brent traded above $115.
Gold Bullish Drivers
Gold currently receives support from:
- Brent below $100;
- lower inflation pressure from energy;
- global political uncertainty;
- AI-market volatility;
- central-bank demand;
- possible softer US inflation this week.
Gold Bearish Drivers
The main risks are:
- strong US labor-market data;
- 4.1% unemployment;
- December Fed-hike probability near 80%;
- potentially hot US CPI;
- a firm Dollar Index near 102.
Gold Fundamental Bias
Mildly Bullish
Gold’s short-term structure has improved.
However, Tuesday’s CPI report could quickly reverse the move if inflation exceeds expectations.
Traders can compare this macro view with current FastPip Trading Signals.
US Jobs Data Changed the Fed Outlook
Friday’s employment report remains one of the biggest drivers of today’s market.
US Nonfarm Payrolls increased by:
165,000
compared with:
65,000 expected
and an upwardly revised:
60,000 previously
The unemployment rate fell from:
4.2%
to:
4.1%
The result was significantly stronger than markets expected.
Read the Reuters US employment report.
October US Employment Results
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Nonfarm Payrolls | 165K | 65K | 60K revised |
| Unemployment Rate | 4.1% | 4.2% | 4.2% |
| Average Hourly Earnings YoY | ~3.1% | 2.9% | ~3.0% |
| Aug + Sep Revisions | +84K | — | — |
The report strengthened expectations that the Federal Reserve has enough economic room to continue tightening.
December Fed-Hike Probability Near 80%
Before Friday’s jobs report, markets assigned roughly a 70% probability to another December rate increase.
After NFP:
Probability ≈ 80%–81%
This is the biggest bearish macro risk for gold today.
The market’s reasoning is straightforward:
Strong Jobs → Less Recession Risk → More Room for Fed Tightening
New York Fed President John Williams also said that the economy has remained resilient but inflation remains too high and must return to the 2% target.
The Federal Reserve’s latest speeches and policy communication can be monitored through the Federal Reserve.
US CPI Is Now the Most Important Market Event
Today’s US calendar is relatively light.
The market is therefore already positioning for Tuesday’s US Consumer Price Index report.
After Friday’s strong payrolls data, CPI could become even more important than usual.
If inflation remains hot:
Strong Jobs + High Inflation
would provide a powerful argument for another December rate increase.
If CPI softens:
Strong Jobs + Lower Inflation
would give the Fed more flexibility.
US CPI Scenario Analysis
Scenario 1: CPI Above Expectations
This would be the most bearish scenario for gold.
Potential reaction:
Fed-Hike Odds ↑
Treasury Yields ↑
DXY ↑
Gold ↓
Nasdaq ↓
Scenario 2: CPI Near Expectations
Markets may keep the December hike as the base case but avoid aggressively increasing the probability.
Gold could remain supported above $4,000.
Scenario 3: CPI Below Expectations
A soft report could materially reduce concerns about another rate increase.
Potential reaction:
Treasury Yields ↓
DXY ↓
Gold ↑
Nasdaq ↑
This would be the strongest bullish macro scenario for gold.
US Dollar Fundamental Analysis
The Dollar Index traded near 102.2 on Monday.
The dollar recorded its largest single-day gain in roughly five months after Friday’s NFP report.
EUR/USD traded near 1.1148, while USD/JPY remained elevated near 158.2.
The latest global-market overview is available through Reuters.
USD Bullish Drivers
- NFP at 165K;
- unemployment at 4.1%;
- December Fed-hike expectations;
- resilient US economic growth;
- relatively high US interest rates.
USD Bearish Drivers
- lower crude oil;
- reduced inflation pressure;
- possible softer CPI;
- improving global risk appetite.
US Dollar Fundamental Bias
Mildly Bullish
The key test is whether Tuesday’s CPI confirms Friday’s hawkish labor signal.
EUR/USD Fundamental Analysis
EUR/USD traded around 1.1148.
The pair remains under pressure because US employment data strengthened expectations for another rate hike.
At the same time, European economic growth remains fragile.
EUR/USD Bullish Scenario
The strongest bullish catalyst would be:
Soft US CPI + Lower Treasury Yields
Potential reaction:
EUR/USD ↑
EUR/USD Bearish Scenario
The strongest bearish combination would be:
Hot CPI + Fed-Hike Probability Above 90%
Potential reaction:
EUR/USD ↓
EUR/USD Fundamental Bias
Neutral to Mildly Bearish
USD/JPY Fundamental Analysis
USD/JPY remained close to 158.2.
The pair continues to benefit from the wide US-Japan interest-rate differential.
However, the Bank of Japan has already signaled that additional tightening remains possible.
USD/JPY Bullish Drivers
- strong US labor market;
- December Fed-hike expectations;
- higher US rates.
USD/JPY Bearish Drivers
- BOJ tightening;
- risk-off demand for yen;
- potential softer US CPI.
USD/JPY Fundamental Bias
Mildly Bullish
Oil Fundamental Analysis Today
Oil remains one of the most important macro variables.
Brent crude traded around:
$98.35 per barrel
while WTI was near:
$91.30
after suffering one of its steepest weekly declines since the COVID period.
Read the latest Reuters oil report.
Why Oil Is Below $100
US President Donald Trump said he was highly unlikely to order additional attacks on Iran as long as diplomatic negotiations continue.
That reduced expectations of further supply disruptions.
Markets are therefore removing part of the geopolitical premium.
-
Oil Bearish Drivers
US-Iran diplomatic progress;
- recovering Middle Eastern exports;
- weak global demand;
- rising production outside the region;
- growing global supply surplus.
JPMorgan estimates global oil supply exceeded consumption by around 1.4 million barrels per day in October.
That is a significant bearish fundamental factor.
Oil Bullish Risks
However, the Middle East remains unstable.
Shipping incidents continue near the Strait of Hormuz.
Houthis also claimed responsibility for an attack on Saudi Aramco’s Riyadh offices.
Therefore:
Oil Risk Premium ↓
but:
Geopolitical Risk ≠ Zero
Oil Fundamental Bias
Neutral to Bearish
The broader short-term trend remains weak while diplomacy continues.
Oil Below $100 Changes the Inflation Narrative
The Daily Fundamental Analysis November 9 2026 highlights one of the most important macro changes since October.
Late October:
Brent > $115
Today:
Brent < $100
That decline could materially reduce:
- gasoline inflation;
- transport costs;
- logistics costs;
- inflation expectations;
- pressure on household spending.
This matters directly for the Fed.
Lower energy inflation could weaken the argument for aggressive tightening even if employment remains strong.
China Producer Inflation Surges to 5.7%
China released important inflation data today.
October Producer Price Inflation accelerated to:
5.7% year-over-year
compared with:
5.0% previously
and:
5.3% expected
This was the fastest increase in nearly four and a half years.
Read the Reuters China inflation report.
China Inflation Results
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| PPI YoY | 5.7% | 5.3% | 5.0% |
| CPI YoY | 0.7% | 0.8% | 0.9% |
| Core CPI YoY | 0.8% | — | 1.0% |
China therefore has a very unusual inflation problem.
Producer costs are rising rapidly.
But consumer inflation remains weak.
What China’s Inflation Data Mean
The message is:
Input Costs ↑
while:
Consumer Demand Weak
This means companies may face margin pressure if they cannot pass higher costs to consumers.
The biggest drivers of producer inflation include:
- oil;
- natural gas;
- mining;
- chemicals;
- energy-intensive manufacturing.
For global markets, China’s data suggest that the Middle East energy shock has not disappeared completely even though spot crude prices are now lower.
China Growth Outlook
China’s economy grew faster than expected in Q3, supported by exports.
However, domestic demand remains weak.
The combination of:
Strong Supply + Weak Household Demand
continues to create a difficult policy environment.
This is important for:
- AUD;
- copper;
- Asian equities;
- industrial commodities.
AUD/USD Fundamental Analysis
AUD is sensitive to China’s economic outlook.
Higher Chinese producer inflation can support commodity-linked revenue in some sectors.
But weak Chinese consumer demand creates a negative counterweight.
AUD/USD Fundamental Bias
Neutral
The pair is likely to remain more sensitive to US CPI and global risk sentiment than today’s China CPI alone.
AI Stocks Attempt to Stabilize
Technology markets are attempting to rebound after last week’s historic selloff.
Asian equities opened strongly.
Japan’s Nikkei gained around 3.5%.
Taiwan equities rose more than 6%.
South Korean equities advanced around 1.8%.
US S&P 500 futures gained approximately 0.6%.
However, last week’s damage remains significant.
The Nasdaq entered correction territory after declining more than 10% from its October high.
Read Reuters’ week-ahead analysis.
Why AI Stocks Are Rebounding
Several factors are helping:
- bargain hunting;
- lower oil prices;
- Friday’s market rebound;
- reduced immediate Middle East escalation risk.
However, the fundamental concerns have not disappeared.
Investors still worry about:
- AI profitability;
- data-center regulation;
- debt financing;
- capital expenditure;
- electricity consumption;
- free cash flow.
AI Earnings Remain Important This Week
Several technology companies report results this week, including:
- CoreWeave;
- Applied Materials;
- Cisco Systems.
These results could provide new evidence about whether AI infrastructure demand remains strong enough to justify enormous investment.
The market’s question remains:
Can AI investment generate sustainable free cash flow?
Nasdaq Fundamental Outlook
Nasdaq enters Monday in recovery mode.
Lower oil prices and improving risk appetite are supportive.
But the index remains technically and fundamentally fragile after last week’s correction.
Nasdaq Bullish Drivers
- dip buying;
- lower oil;
- lower inflation expectations;
- technology earnings.
Nasdaq Bearish Drivers
- AI regulation;
- high valuations;
- December Fed tightening;
- financing pressure;
- potential hot CPI.
Nasdaq Fundamental Bias
Neutral / High Volatility
Tuesday’s CPI could become the next major catalyst.
S&P 500 Fundamental Outlook
S&P 500 futures gained approximately 0.6% in Monday’s early session.
The broader index remains more diversified than Nasdaq and therefore less vulnerable to a concentrated AI selloff.
However, technology still has a major influence on index performance.
S&P 500 Fundamental Bias
Neutral to Mildly Bullish
Lower crude oil and improving risk sentiment provide support.
Today’s Key Economic Events — November 9, 2026
The Daily Fundamental Analysis November 9 2026 begins a relatively lighter US macro session before Tuesday’s critical inflation report.
| Time / Status | Currency | Event | Actual | Forecast | Previous |
|---|---|---|---|---|---|
| Released | CNY | PPI YoY | 5.7% | 5.3% | 5.0% |
| Released | CNY | CPI YoY | 0.7% | 0.8% | 0.9% |
| Released | CNY | Core CPI YoY | 0.8% | — | 1.0% |
| Today | USD | Fed / Rate Expectations | Market Focus | — | — |
| Tuesday | USD | US CPI | Upcoming | Pending | Previous Month |
| Friday | USD | US PPI | Upcoming | Pending | Previous Month |
For live release times and Actual values, use the FastPip Economic Calendar.
Why Today’s Light US Calendar Still Matters
The absence of a major tier-one US data release does not mean markets will be quiet.
Positioning ahead of Tuesday’s CPI can move:
- Treasury yields;
- gold;
- DXY;
- Nasdaq;
- EUR/USD.
Markets may also react sharply to Fed speakers because the December decision remains highly sensitive to inflation.
Daily Fundamental Analysis November 9 2026: Market Bias
| Asset | Fundamental Bias | Confidence | Main Driver |
|---|---|---|---|
| Gold / XAUUSD | Mildly Bullish | High | Lower oil + inflation relief |
| Silver / XAGUSD | Bullish | Moderate | Gold + precious metals |
| DXY | Mildly Bullish | Moderate | Strong NFP + Fed |
| EUR/USD | Neutral → Bearish | Moderate | USD strength |
| GBP/USD | Neutral | Low | USD + BoE |
| USD/JPY | Mildly Bullish | Moderate | Rate differential |
| AUD/USD | Neutral | Moderate | China + USD |
| S&P 500 | Neutral → Bullish | Moderate | Risk recovery |
| Nasdaq | Neutral / Volatile | High | AI + CPI risk |
| Brent Oil | Neutral → Bearish | High | Iran diplomacy |
| WTI Oil | Neutral → Bearish | High | Supply surplus |
| US Treasuries | Neutral | Moderate | CPI anticipation |
7 Trader Watchpoints for November 9, 2026
1. Gold Above $4,100
Gold has rebuilt momentum above an important psychological threshold.
Holding above $4,000 keeps the broader recovery intact.
2. Brent Below $100
This is one of the most important bullish developments for gold and risk assets.
3. DXY Near 102.2
The dollar remains supported by Friday’s strong jobs report.
4. December Fed-Hike Probability
Markets still price approximately an 80% probability of another increase.
5. Tuesday’s US CPI
This is the single biggest scheduled macro risk.
6. AI Equity Recovery
Today’s rebound needs confirmation from earnings and broader risk flows.
7. China PPI at 5.7%
Producer inflation shows that energy-driven cost pressure remains significant globally.
Combined Market Scenario Analysis
Scenario 1: Oil Remains Below $100 + Soft CPI Expectations
This is the strongest bullish setup for gold.
Potential reaction:
Gold ↑
Treasury Yields ↓
DXY ↓
Nasdaq ↑
Scenario 2: CPI Expectations Rise Ahead of Tuesday
Potential reaction:
Treasury Yields ↑
DXY ↑
Gold ↓
Scenario 3: AI Rebound Continues
Potential reaction:
Nasdaq ↑
Safe-Haven Treasury Demand ↓
Gold may remain supported if oil stays weak.
Scenario 4: AI Selloff Returns
Potential reaction:
Nasdaq ↓
Treasury Demand ↑
Yields ↓
Gold ↑ eventually
Scenario 5: Iran Talks Collapse
Potential reaction:
Oil ↑ sharply
Inflation Expectations ↑
Fed-Hike Probability ↑
Gold Volatility ↑
Final Daily Fundamental Outlook
The Daily Fundamental Analysis November 9 2026 shows global markets starting the week with a better inflation backdrop but a more hawkish Federal Reserve outlook.
Gold has climbed above $4,120.
Oil is below $100.
Asian equities are rebounding.
Technology stocks are attempting to recover.
These are supportive developments.
However, Friday’s employment report significantly strengthened the case for another Federal Reserve rate increase.
Payroll growth reached 165K.
Unemployment fell to 4.1%.
Markets now price roughly an 80% chance of another hike.
This means Tuesday’s CPI report becomes critical.
For gold, the strongest bullish combination is:
Soft CPI + Brent Below $100 + Lower Treasury Yields
The strongest bearish combination is:
Hot CPI + Fed-Hike Probability Above 90% + Stronger DXY
For the dollar:
CPI + Fed Expectations
For Nasdaq:
CPI + AI Earnings
For oil:
Iran Diplomacy + Global Supply Surplus
For China-sensitive markets:
PPI Inflation vs Weak Consumer Demand
The central market question today is:
Can falling oil prices offset the hawkish message from Friday’s strong US jobs report?
If inflation cools, gold could extend its recovery.
If Tuesday’s CPI remains hot, the Federal Reserve tightening narrative could regain control of markets.
For definitions of CPI, PPI, Treasury yields, Federal Reserve policy and other market concepts, visit the FastPip Financial Glossary.
Frequently Asked Questions
What Is the Daily Fundamental Analysis November 9 2026 Outlook for Gold?
The Daily Fundamental Analysis November 9 2026 suggests a mildly bullish short-term outlook for gold because lower oil prices are reducing inflation concerns.
What Is Gold Trading at Today?
Spot gold traded near $4,123.46 per ounce, up approximately 1.4%.
Why Is Gold Rising Today?
Gold is benefiting from lower crude oil prices, softer inflation expectations and renewed demand following last week’s volatility.
What Is Brent Oil Trading At?
Brent crude traded near $98.35 per barrel, while WTI was around $91.30.
Why Is Oil Below $100?
Oil has fallen as US-Iran diplomatic talks reduce fears of further supply disruptions and global supply conditions improve.
What Is the Probability of a December Fed Rate Hike?
Markets currently price approximately an 80%–81% probability of another Federal Reserve rate increase.
What Was Friday’s NFP Result?
US Nonfarm Payrolls increased by 165K, compared with approximately 65K expected.
What Happened to the Unemployment Rate?
The US unemployment rate declined from 4.2% to 4.1%.
What Did China CPI Show?
China’s consumer inflation slowed to 0.7% year-over-year, below the approximately 0.8% forecast.
What Did China PPI Show?
Producer-price inflation accelerated to 5.7%, the fastest pace in nearly four and a half years.
What Is the Biggest Market Event This Week?
Tuesday’s US Consumer Price Index is the most important scheduled macro release because it could significantly change expectations for the December Federal Reserve meeting.
What Should Traders Watch After the Daily Fundamental Analysis November 9 2026?
Following the Daily Fundamental Analysis November 9 2026, traders should monitor gold above $4,100, Brent below $100, DXY near 102.2, December Fed-hike expectations, Tuesday’s US CPI, Treasury yields, AI-sector earnings, Nasdaq volatility, China inflation and developments in US-Iran negotiations.
 Check Our
 Whether you’re a day trader or a long-term investor, FastPip gives you the tools to trade smarter, not harder.