Daily Fundamental Analysis October 23 2026 | FastPip
Daily Fundamental Analysis October 23 2026: 7 Critical Market Risks
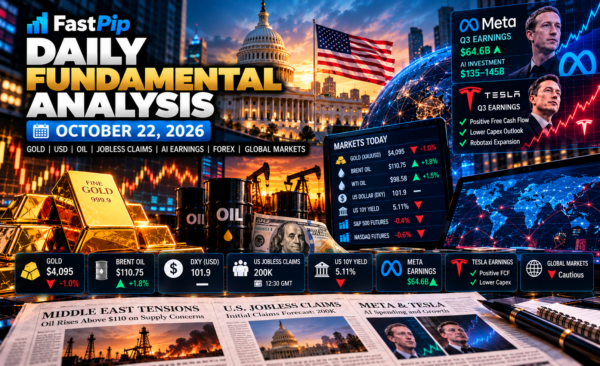
The Daily Fundamental Analysis October 23 2026 begins with gold trading close to the psychologically important $4,000 level, Brent crude above $114, US Treasury yields falling sharply below 5%, and global technology markets still under pressure from renewed concerns about artificial intelligence financing.
Gold traded near $4,021 per ounce during Friday’s session after touching its lowest level since July 20.
The metal is heading toward its steepest weekly decline in more than four months, down approximately 3.6% this week, as high oil prices reinforce expectations that US interest rates may remain elevated for longer.
Oil is moving in the opposite direction.
Brent climbed above $114 per barrel, reaching a fresh five-month high, while WTI moved above $100 as escalating Middle East tensions increased concerns about physical supply disruption.
At the same time, the Nasdaq suffered another sharp selloff on Thursday as investors questioned the enormous funding requirements of AI infrastructure projects.
This triggered the largest one-day rally in US Treasuries in more than three years, pushing the 10-year yield back below 5%.
Today’s seven major market drivers are:
- Gold defending the $4,000 region
- Brent crude above $114
- US Flash Manufacturing and Services PMIs
- Michigan Consumer Sentiment
- Treasury yields below 5%
- AI-sector financing concerns
- Japan inflation above the BOJ target
For live updates during the session, traders can follow the FastPip Economic Calendar.
Daily Fundamental Analysis October 23 2026: Global Market Snapshot
| Asset / Market | Latest Reported Level / Move | Fundamental Signal |
|---|---|---|
| Gold / XAUUSD | ~$4,021 | Bearish |
| Silver / XAGUSD | ~$54.31 | Bearish |
| Brent Oil | ~$114.47 | Strongly Bullish |
| WTI Oil | ~$100.84 | Bullish |
| US 10Y Yield | ~4.97% | Sharply Lower |
| US 2Y Yield | ~4.66% | Lower |
| USD/JPY | ~156.91 | Softer |
| Nasdaq | Previous Session > -2% | Risk-Off |
| Nikkei 225 | ~-0.5% | Bearish |
| KOSPI | Recovered from Heavy Losses | Volatile |
| CSI 300 | ~+0.8% | Recovery |
Reuters reported that the Nasdaq fell more than 2% on Thursday as AI-funding concerns returned, while the US 10-year Treasury yield dropped around 19 basis points in its biggest daily decline since March 2023. Read the Reuters global-markets report.
Gold Fundamental Analysis Today
Gold remains under heavy pressure.
Spot gold traded around $4,021 per ounce, after falling to its lowest level since July.
US December gold futures were near $4,035.50.
Gold is now heading for its worst weekly performance since June.
Reuters reported that bullion has lost around 3.6% this week, as elevated oil prices strengthen expectations that the Federal Reserve may need to keep interest rates restrictive for longer. Read the Reuters gold-market report.
Why Gold Is Falling Despite Lower Treasury Yields
Normally, falling Treasury yields should support gold.
That relationship still matters.
However, another force is currently stronger:
Oil-driven inflation expectations.
Brent above $114 raises the risk that inflation remains persistent.
The market therefore faces an unusual combination:
Treasury Yields ↓
but:
Inflation Expectations ↑
Gold is struggling because investors are not yet convinced that lower yields represent genuine monetary-policy easing.
Instead, bond yields are falling partly because of safe-haven demand created by the technology selloff.
The $4,000 Gold Level Is Critical
The psychological $4,000 region is now one of the most important levels in global markets.
A clean break below it could signal that investors are increasingly pricing:
- sticky inflation;
- high real interest rates;
- delayed Fed easing;
- stronger long-term dollar demand.
Reuters cited analysts warning that a sustained break below $4,000 could materially weaken gold’s short-term structure.
Gold Bullish Scenario
Gold could rebound if:
- Treasury yields continue falling;
- Brent retreats below $110;
- US PMIs disappoint;
- Michigan sentiment falls sharply;
- AI-market stress intensifies.
Potential reaction:
Gold ↑
Treasuries ↑
DXY ↓ / Mixed
Nasdaq ↓
Gold Bearish Scenario
Gold could break below $4,000 if:
- US PMIs beat expectations;
- consumer sentiment remains resilient;
- oil rises toward $116–120;
- Treasury yields rebound above 5%;
- Fed rate-hike expectations increase again.
Potential reaction:
Gold ↓
USD ↑
USD/JPY ↑
Treasury Yields ↑
Gold Fundamental Bias
Bearish
The strongest short-term risk remains a confirmed break below $4,000.
However, sharply lower Treasury yields may limit the speed of further downside.
Traders can compare the macro outlook with current FastPip Trading Signals.
Oil Fundamental Analysis Today
Oil is again the dominant inflation risk.
Brent crude rose more than 1% to approximately $114.47 per barrel.
WTI traded around $100.84.
Brent is now at its highest level in around five months.
Reuters reported that renewed Houthi attacks inside Saudi Arabia increased fears of further disruption to Middle Eastern energy supply. Read the Reuters oil report.
Why Oil Is Rising
The market is increasingly focused on physical supply risk.
Major concerns include:
- attacks inside Saudi Arabia;
- Persian Gulf security;
- Strait of Hormuz risk;
- Bab el-Mandeb shipping disruption;
- Saudi Aramco operational risk;
- tanker availability;
- insurance and freight costs.
Saudi Aramco reportedly ordered the evacuation of its headquarters in Dhahran as security conditions deteriorated.
Oil therefore continues to carry a large geopolitical risk premium.
Oil Bullish Drivers
- Middle East escalation;
- Houthi attacks;
- Saudi supply risk;
- shipping chokepoint disruption;
- tight physical supply;
- elevated insurance costs.
Oil Bearish Drivers
- diplomatic de-escalation;
- strategic reserve releases;
- additional Russian exports;
- global demand destruction;
- slower economic growth.
Oil Fundamental Bias
Strongly Bullish / Extremely High Volatility
As long as Middle East supply risk remains elevated, the broader oil trend remains supported.
Oil Is Now the Fed’s Biggest Inflation Problem
Brent above $114 creates direct inflation pressure through:
- gasoline;
- transportation;
- manufacturing;
- logistics;
- food distribution;
- airline costs;
- household inflation expectations.
The macro transmission mechanism is:
Oil ↑ → Inflation Expectations ↑ → Fed Easing Delayed → Gold Pressure
This relationship is increasingly important ahead of next week’s Federal Reserve meeting.
Federal Reserve Outlook
The Federal Reserve meets on October 27–28.
Markets continue to expect policymakers to leave rates unchanged at that meeting.
However, expectations for a December increase remain substantial.
According to the latest Reuters gold-market report, traders currently place the probability of a December rate increase at roughly 76%.
That is lower than earlier in the week because the technology-sector selloff has raised concerns about financial conditions and economic growth.
This creates a major policy conflict:
Inflation Risk → Hawkish
while:
AI / Financial Stress → Dovish
The Fed must decide which risk deserves more attention.
Treasury Yields Collapse as AI Concerns Intensify
The US bond market produced one of the most important moves of the week.
The 10-year Treasury yield fell more than 19 basis points on Thursday, its largest one-day decline since March 2023.
It traded near 4.97% on Friday, below the key 5% level.
The 2-year yield also fell approximately 19 basis points and traded around 4.66%.
Reuters reported that investors moved aggressively into Treasuries as concerns about AI infrastructure financing intensified. Read the Reuters global-markets analysis.
Why the Treasury Move Matters
Normally, a 19-basis-point drop in yields would be extremely bullish for gold and technology stocks.
Instead:
Gold Fell
and:
Nasdaq Fell
This tells us the bond rally was driven primarily by:
Risk Aversion
rather than:
Confidence in Lower Inflation
That distinction matters.
If yields remain below 5% because inflation is cooling, gold would benefit.
If yields remain lower because investors fear an AI-sector financial shock, gold may eventually benefit, but equity volatility could remain extremely high.
AI Stocks Remain Under Pressure
The Nasdaq fell more than 2% on Thursday.
Meta declined almost 8% after the company reported its first cash outflow in more than a decade because of AI-related spending.
Tesla fell around 3.1% after reducing its 2026 capital-spending plans.
Reuters reported that concerns about the enormous funding needs of AI projects continue to weigh on global technology shares. Read the Reuters AI-market report.
The AI Trade Is Changing
The AI investment story is entering a new phase.
Investors are no longer asking only:
How quickly can AI revenue grow?
They are increasingly asking:
How much debt is required to finance the infrastructure?
The biggest costs include:
- data centers;
- semiconductors;
- electricity;
- cooling;
- networking;
- cloud infrastructure;
- specialized AI hardware.
The market is becoming much more selective.
Companies with strong free cash flow may continue to receive support.
Highly leveraged AI infrastructure companies could face increasing pressure.
Nasdaq Fundamental Outlook
The Nasdaq remains highly vulnerable.
Lower Treasury yields should theoretically support technology valuations.
But investors are now worried about AI capital requirements and profitability.
Nasdaq Bullish Scenario
Technology equities could recover if:
- Treasury yields remain below 5%;
- US PMIs soften moderately;
- AI credit markets stabilize;
- major companies reduce capex concerns.
Nasdaq Bearish Scenario
The correction could continue if:
- AI funding costs rise;
- corporate guidance weakens;
- oil continues higher;
- economic growth slows sharply.
Nasdaq Fundamental Bias
Bearish / High Volatility
The decline in yields provides some support, but AI financing concerns remain the dominant issue.
S&P 500 Fundamental Outlook
S&P 500 futures traded around 0.2% lower in early Friday markets.
The index remains less exposed to AI concentration than the Nasdaq, but technology still represents a major share of expected earnings growth.
The market is therefore entering a more selective environment.
Strong free cash flow and balance-sheet quality are becoming increasingly important.
S&P 500 Fundamental Bias
Neutral to Mildly Bearish
Lower Treasury yields are supportive, but technology-sector stress and high oil prices create significant downside risk.
Japan Inflation Strengthens the BOJ Tightening Case
Japan released important inflation data today.
Core CPI accelerated to 2.1% year-over-year in September, matching expectations and rising from 1.7% previously.
An inflation measure excluding both fresh food and fuel increased 2.4%, compared with 1.9% previously.
Reuters reported that inflation has now moved above the Bank of Japan’s 2% target, strengthening the case for another rate increase later in the year. Read the Reuters Japan CPI report.
Japan CPI Results
| Japan Inflation Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Core CPI YoY | 2.1% | 2.1% | 1.7% |
| Core-Core CPI YoY | 2.4% | — | 1.9% |
| Goods Inflation | 2.8% | — | 2.6% |
| Services Inflation | 1.5% | — | 1.2% |
Why Japan CPI Matters
The BOJ raised rates last month to 1.25%, the highest level in 31 years.
The central bank is expected to hold rates next week.
However, officials may raise inflation forecasts and signal further tightening.
That could provide additional support for the Japanese yen.
USD/JPY Fundamental Analysis
USD/JPY traded around 156.91 after falling approximately 0.9% on Thursday.
Two forces are supporting the yen:
- falling US Treasury yields;
- stronger Japanese inflation.
USD/JPY Bullish Scenario
The pair could rebound if:
- US PMIs beat forecasts;
- US yields return above 5%;
- Fed expectations become more hawkish.
USD/JPY Bearish Scenario
The pair could fall if:
- US data disappoint;
- Treasury yields continue lower;
- BOJ tightening expectations increase.
USD/JPY Fundamental Bias
Neutral to Mildly Bearish
French PMI Adds Pressure to the Euro
France delivered another negative macro surprise today.
The Flash Services PMI fell to 48.4 in October from 51.2 in September.
Markets had expected approximately 50.7.
Manufacturing PMI also fell to 49.3, compared with 50.6 previously and a 50.5 forecast.
The Composite PMI declined to 48.4, clearly below the 50 level separating expansion from contraction.
Reuters reported that French companies linked weaker activity to political uncertainty, tighter financial conditions and falling demand. Read the Reuters French PMI report.
France Flash PMI
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Services PMI | 48.4 | 50.7 | 51.2 |
| Manufacturing PMI | 49.3 | 50.5 | 50.6 |
| Composite PMI | 48.4 | 50.5 | 51.1 |
This is fundamentally negative for the euro.
EUR/USD Fundamental Analysis
EUR/USD faces pressure from two sides.
Lower US Treasury yields are supportive.
But deteriorating French economic data and European fiscal concerns are bearish.
France’s 10-year government-bond yield remains close to historically high levels as investors worry about fiscal sustainability.
EUR/USD Bullish Scenario
EUR/USD could rise if:
- US PMIs disappoint;
- Treasury yields continue falling;
- Michigan sentiment weakens.
EUR/USD Bearish Scenario
The pair could fall if:
- US PMI data remain strong;
- French/Eurozone PMIs deteriorate further;
- European sovereign spreads widen.
EUR/USD Fundamental Bias
Neutral to Mildly Bearish
US Flash PMIs: Today’s Main US Growth Test
The most important scheduled US data today are the October Flash PMIs.
Both Manufacturing and Services data are scheduled for 12:45 GMT.
US PMI Forecasts
| US PMI Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Manufacturing PMI | Pending | 55.4 | 55.9 |
| Services PMI | Pending | 57.9 | 58.8 |
| Composite PMI | Pending | — | 58.4 |
Readings above 50 indicate expansion.
Both forecasts remain comfortably above 50, suggesting the US private sector is still expanding.
Today’s calendar details are available through Investing.com’s US economic calendar preview.
US PMI Scenario Analysis
Scenario 1: PMIs Beat Expectations
If Manufacturing and Services PMIs remain exceptionally strong:
US Growth Expectations ↑
Treasury Yields ↑
USD ↑
Gold ↓
USD/JPY ↑
This would reinforce the higher-for-longer Fed narrative.
Scenario 2: PMIs Near Expectations
Markets may remain focused on oil, AI risk and next week’s Fed meeting.
Scenario 3: PMIs Miss Expectations
A meaningful slowdown could reinforce the recent Treasury rally.
Potential reaction:
Treasury Yields ↓
USD ↓
Gold ↑
However, a severe miss could create additional equity-market concerns.
Michigan Consumer Sentiment
The preliminary University of Michigan Consumer Sentiment reading is scheduled for 13:00 GMT.
The forecast is:
46.3
compared with:
48.1 previously
Consumer sentiment has weakened as households respond to:
- high energy prices;
- elevated interest rates;
- expensive housing;
- inflation;
- financial-market volatility.
The official survey series is available through the University of Michigan Surveys of Consumers.
Consumer Sentiment Scenario
Above 46.3
Potential reaction:
USD Support
Treasury Yields ↑
Gold Pressure
Below 46.3
Potential reaction:
Treasury Yields ↓
Gold Support
USD Pressure
However, extremely weak sentiment could also increase recession fears.
Today’s Key Economic Events — October 23, 2026
The Daily Fundamental Analysis October 23 2026 includes important already released data and upcoming US macro releases.
All times are shown in GMT / UTC.
| Time GMT | Currency | Event | Actual | Forecast | Previous |
|---|---|---|---|---|---|
| Released | JPY | Core CPI YoY | 2.1% | 2.1% | 1.7% |
| Released | JPY | Core-Core CPI YoY | 2.4% | — | 1.9% |
| Released | EUR | France Services PMI | 48.4 | 50.7 | 51.2 |
| Released | EUR | France Manufacturing PMI | 49.3 | 50.5 | 50.6 |
| Released | EUR | France Composite PMI | 48.4 | 50.5 | 51.1 |
| 12:45 | USD | Flash Manufacturing PMI | Pending | 55.4 | 55.9 |
| 12:45 | USD | Flash Services PMI | Pending | 57.9 | 58.8 |
| 12:45 | USD | Flash Composite PMI | Pending | — | 58.4 |
| 13:00 | USD | Michigan Consumer Sentiment | Pending | 46.3 | 48.1 |
| 13:00 | USD | Michigan Consumer Expectations | Pending | 47.3 | 46.3 |
| 16:00 | USD | Baker Hughes Oil Rig Count | Pending | — | 459 |
| 16:00 | USD | Baker Hughes Total Rig Count | Pending | — | 603 |
For live actual values after release, monitor the FastPip Economic Calendar.
Baker Hughes Rig Count
The US Baker Hughes rig count is scheduled for 16:00 GMT.
The previous oil-rig count was 459.
The total rig count was 603.
A rising rig count can signal higher future US production capacity.
However, because current oil prices are being driven heavily by geopolitical supply risk, today’s rig-count data are unlikely to dominate the energy market.
US Dollar Fundamental Analysis
The US dollar is receiving conflicting signals.
The bullish factors are:
- persistent inflation;
- oil above $114;
- potential December Fed tightening;
- relatively resilient US growth.
The bearish factors are:
- Treasury yields below 5%;
- lower Fed tightening expectations;
- AI-related financial stress;
- safe-haven demand flowing into Treasuries rather than exclusively into USD.
US Dollar Fundamental Bias
Neutral
Today’s PMI and consumer-sentiment releases could determine whether the dollar regains momentum.
Daily Fundamental Analysis October 23 2026: Market Bias
| Asset | Fundamental Bias | Confidence | Main Driver |
|---|---|---|---|
| Gold / XAUUSD | Bearish | High | Oil + Fed expectations |
| Silver / XAGUSD | Bearish | Moderate | Gold weakness |
| DXY | Neutral | Moderate | Inflation vs lower yields |
| EUR/USD | Neutral → Bearish | Moderate | France PMI |
| GBP/USD | Neutral | Low | USD direction |
| USD/JPY | Neutral → Bearish | Moderate | Japan CPI + US yields |
| S&P 500 | Neutral → Bearish | Moderate | AI concerns |
| Nasdaq | Bearish / Volatile | High | AI financing |
| Brent Oil | Strongly Bullish | High | Middle East risk |
| WTI Oil | Bullish | High | Supply risk |
| US Treasuries | Bullish | High | Risk aversion |
7 Trader Watchpoints for October 23, 2026
1. Gold at the $4,000 Threshold
This is the single most important gold level today.
A clean break below $4,000 could accelerate selling.
2. Brent Above $114
Oil is now the dominant inflation threat.
Another move toward $116–120 would increase pressure on central banks.
3. US 10-Year Yield Below 5%
The Treasury rally is limiting some of gold’s downside.
A rebound above 5% would be bearish for bullion.
4. US Flash PMIs
PMIs will show whether the US economy remains resilient despite high rates.
5. Michigan Consumer Sentiment
Consumer confidence is expected to weaken again.
6. AI Credit Markets
Treasury yields are falling partly because investors are becoming more defensive around AI financing.
7. Japan and BOJ Expectations
Higher Japanese inflation increases the probability of additional BOJ tightening later this year.
Combined Scenario Analysis
Scenario 1: Strong PMIs + Oil Above $115
This would be the most bearish combination for gold.
Potential reaction:
Treasury Yields ↑
DXY ↑
Gold ↓
USD/JPY ↑
Scenario 2: Weak PMIs + Weak Consumer Sentiment
This would increase growth concerns.
Potential reaction:
Treasuries ↑
Yields ↓
Gold ↑
USD ↓
However, equity markets could remain weak.
Scenario 3: AI Selloff Intensifies + Treasury Yields Fall
Potential reaction:
Nasdaq ↓
Treasuries ↑
Gold Eventually Supported
This is an unusual risk-off scenario because safe-haven demand may initially favor government bonds more strongly than gold.
Scenario 4: Oil Breaks Above $118
Potential reaction:
Inflation Expectations ↑
Fed-Hike Risk ↑
Treasury Yields ↑
Gold ↓ / Highly Volatile
Scenario 5: Oil Retreats + PMIs Moderate
This would be the most constructive environment for gold and growth stocks.
Potential reaction:
Gold ↑
Nasdaq ↑
DXY ↓
Final Daily Fundamental Outlook
The Daily Fundamental Analysis October 23 2026 shows global markets ending the week in an unusual macroeconomic environment.
Gold is approaching the critical $4,000 region.
Oil is trading above $114.
Treasury yields have fallen below 5%.
Technology stocks are under pressure.
Normally, lower Treasury yields would be strongly bullish for gold.
But the current yield decline is being driven by financial-market risk rather than falling inflation.
At the same time, high oil prices continue to increase inflation expectations.
This explains why gold has failed to benefit fully from the Treasury rally.
The US dollar is also receiving conflicting signals.
Persistent inflation and high oil are supportive.
Lower Treasury yields are negative.
For equities, the AI investment narrative has changed.
Investors increasingly want evidence of sustainable free cash flow rather than simply aggressive spending.
For gold, the strongest bullish combination today is:
Weak US PMIs + Lower Consumer Sentiment + Treasury Yields Below 5% + Oil Retreat
The strongest bearish combination is:
Strong US PMIs + Brent Above $115 + Treasury Yield Rebound
For Nasdaq, the key variable remains:
AI Financing Risk
For the dollar:
US Growth + Treasury Yields
The central market question today is:
Can falling Treasury yields protect gold and risk assets from the inflation shock created by $114 oil?
The answer will determine whether gold can defend $4,000 and whether the technology selloff stabilizes before next week’s Federal Reserve meeting.
For definitions of PMI, consumer sentiment, Treasury yields and inflation, visit the FastPip Financial Glossary.
Frequently Asked Questions
What Is the Daily Fundamental Analysis October 23 2026 Outlook for Gold?
The Daily Fundamental Analysis October 23 2026 suggests a bearish short-term outlook for gold while crude oil remains above $114 and rate expectations stay restrictive.
What Is Gold Trading at Today?
Spot gold traded near $4,021 per ounce and briefly touched its lowest level since July 20.
How Much Has Gold Fallen This Week?
Gold has fallen approximately 3.6% this week, putting it on course for its steepest weekly decline since June.
Why Is Gold Falling Even Though Treasury Yields Are Lower?
Treasury yields are declining because of safe-haven demand caused by technology-market stress, while high oil prices are simultaneously increasing inflation and higher-for-longer interest-rate expectations.
Why Is Oil Above $114?
Oil is rising because of renewed Houthi attacks in Saudi Arabia and concerns about further disruption to Middle Eastern energy supply.
What Time Are US PMIs Released Today?
US Flash Manufacturing, Services and Composite PMIs are scheduled for 12:45 GMT.
What Is the US Manufacturing PMI Forecast?
The Manufacturing PMI is expected at 55.4, compared with 55.9 previously.
What Is the US Services PMI Forecast?
The Services PMI is expected at 57.9, compared with 58.8 previously.
What Is the Michigan Consumer Sentiment Forecast?
Consumer Sentiment is expected at 46.3, compared with 48.1 previously.
What Did Japan CPI Show?
Japan’s core CPI accelerated to 2.1%, while the core-core measure increased to 2.4%, strengthening expectations for additional BOJ tightening.
What Happened to French PMI?
France’s Composite PMI fell to 48.4, indicating contraction, compared with 51.1 previously.
What Should Traders Watch After the Daily Fundamental Analysis October 23 2026?
Following the Daily Fundamental Analysis October 23 2026, traders should monitor gold around $4,000, Brent above $114, US Flash PMIs, Michigan Consumer Sentiment, the 10-year Treasury yield below 5%, DXY, Nasdaq volatility, AI financing conditions and next week’s Federal Reserve meeting.
 Check Our
 Whether you’re a day trader or a long-term investor, FastPip gives you the tools to trade smarter, not harder.