Daily Fundamental Analysis October 19 2026 | FastPip
Daily Fundamental Analysis October 19 2026: 7 Critical Market Drivers for Gold, USD & Forex
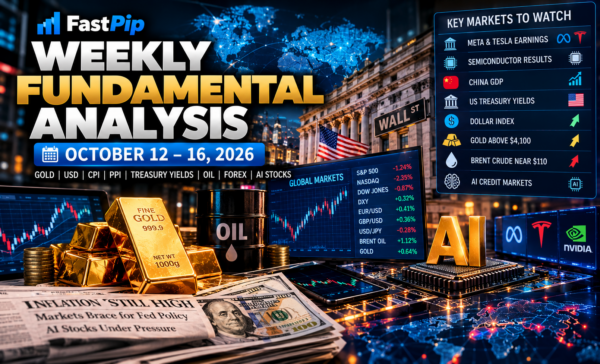
The Daily Fundamental Analysis October 19 2026 begins with gold moving higher, oil prices retreating, Chinese economic growth beating expectations, and global investors preparing for a decisive week of major technology earnings.
Gold gained around 0.4% during Monday trading to approximately $4,182 per ounce, supported by lower oil prices and declining US Treasury yields. Lower energy prices are easing some inflation concerns, while falling yields reduce the opportunity cost of holding non-yielding bullion.
China delivered one of today’s most important macro surprises.
Third-quarter GDP grew 4.5% year-over-year, beating the Reuters consensus forecast of 4.4% and accelerating from 4.3% in Q2. Industrial production and retail sales also exceeded expectations, although the country’s property sector remains weak.
At the same time, Brent crude dropped toward $108 per barrel after the United States eased some restrictions affecting Russian energy exports.
However, Middle East shipping disruptions remain severe, meaning oil volatility is unlikely to disappear quickly.
Today’s seven major market drivers are:
- China GDP beating expectations
- Gold rising above $4,180
- Oil falling after changes to Russian sanctions
- US Treasury yields remaining under pressure
- The Dollar Index stabilizing near 101.8
- AI and semiconductor earnings risk
- US housing sentiment later today
For updated economic releases throughout the session, traders should monitor the FastPip Economic Calendar.
Daily Fundamental Analysis October 19 2026: Global Market Snapshot
| Asset / Market | Latest Reported Level / Move | Fundamental Signal |
|---|---|---|
| Gold / XAUUSD | ~$4,182 | Mildly Bullish |
| DXY | ~101.83 | Neutral |
| EUR/USD | ~1.1225 | Mildly Bearish |
| USD/JPY | ~158.00 | Elevated |
| Brent Oil | ~$108 | Bearish Intraday |
| WTI Oil | Near $100 | Bearish Intraday |
| S&P 500 Futures | +0.8% | Bullish |
| Nasdaq Futures | +1.3% | Bullish |
| Nikkei 225 | -0.7% | Risk-Off |
| China Q3 GDP | +4.5% YoY | Better Than Expected |
The market picture is mixed.
Lower oil and Treasury yields are helping gold and US equity futures.
However, Asian equities remain cautious because investors are still concerned about the financing requirements of the global AI investment boom.
China GDP Beats Expectations
China’s economy expanded 4.5% year-over-year in the third quarter, accelerating from 4.3% in Q2.
The result exceeded the Reuters consensus estimate of 4.4%.
Quarter-on-quarter GDP increased approximately 1.2%.
China Q3 GDP Data
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| GDP YoY Q3 | 4.5% | 4.4% | 4.3% |
| GDP QoQ Q3 | 1.2% | — | — |
The headline growth figure is encouraging.
However, the composition of China’s growth remains uneven.
Exports and manufacturing continue to outperform household consumption and property investment.
This means the economy remains heavily dependent on external demand and industrial production.
China Industrial Production Beats Forecast
September industrial production increased 5.5% year-over-year.
That exceeded the 5.4% forecast and accelerated from 5.2% previously.
| China Industrial Production | Actual | Forecast | Previous |
|---|---|---|---|
| YoY | 5.5% | 5.4% | 5.2% |
The stronger industrial reading is positive for:
- industrial metals;
- copper demand;
- regional manufacturing;
- commodity-linked currencies.
China’s high-tech manufacturing sector continues to provide an important source of growth.
China Retail Sales Surprise Higher
Retail Sales increased 1.1% year-over-year in September.
That was more than twice the 0.5% consensus forecast and improved from only 0.4% in August.
| China Retail Sales | Actual | Forecast | Previous |
|---|---|---|---|
| YoY | 1.1% | 0.5% | 0.4% |
This is an improvement.
However, a 1.1% annual increase remains relatively weak for an economy the size of China.
Consumer confidence continues to suffer from the multi-year property downturn.
China’s Property Market Remains the Weak Point
September new-home prices fell approximately 0.1% month-over-month.
Prices were down around 2.8% year-over-year.
China’s housing downturn has now lasted more than three years and continues to affect household wealth, consumer confidence and local-government revenue.
This creates an important contradiction.
China Manufacturing ↑
China Exports ↑
but:
Property Weak + Consumption Weak
The result is a highly uneven recovery.
Market Impact of Stronger China Data
Stronger Chinese growth can provide support for:
AUD
Copper
Asian Equities
and:
Industrial Commodities
However, because domestic demand remains weak, the data are not strong enough to remove concerns about China’s structural slowdown.
Gold Fundamental Analysis Today
Gold moved higher during Monday trading.
Spot bullion rose approximately 0.4% to $4,182.30 per ounce, while US December futures increased roughly 0.5% to around $4,203.50.
The primary catalyst is the decline in oil prices.
Lower oil reduces immediate inflation pressure.
That can reduce upward pressure on Treasury yields.
For gold, the transmission mechanism is:
Oil ↓ → Inflation Expectations ↓ → Treasury Yields ↓ → Gold ↑
Gold is also benefiting from continued uncertainty surrounding AI investments and geopolitical risks.
Gold Bullish Drivers
Gold is currently supported by:
- falling oil prices;
- lower Treasury yields;
- AI-related financial uncertainty;
- geopolitical risk;
- weaker near-term Fed tightening expectations;
- persistent global debt concerns.
Gold Bearish Drivers
The main risks remain:
- high US inflation;
- a potential December Fed rate hike;
- renewed Treasury-yield strength;
- oil returning above $110;
- stronger US growth data.
Federal Reserve Expectations
Market pricing indicates only a relatively small probability of a rate increase at the October meeting.
However, expectations for another increase by December remain considerably higher.
Reuters reported market pricing of approximately 13% for an October hike and around 89% for a hike by December.
This remains a major risk for bullion.
Gold Bullish Scenario
Gold could extend its recovery if:
- Brent continues falling;
- Treasury yields decline;
- DXY falls below 101.5;
- AI earnings disappoint;
- financial-market stress increases.
Potential reaction:
Gold ↑
Treasuries ↑
USD Mixed
Nasdaq ↓
Gold Bearish Scenario
Gold could weaken if:
- technology earnings are very strong;
- risk appetite returns;
- Treasury yields rebound;
- oil rises above $110;
- Fed expectations become more hawkish.
Gold Fundamental Bias
Mildly Bullish
Lower yields and softer energy prices currently provide a supportive macro environment.
Traders can compare this fundamental view with current FastPip Trading Signals.
US Dollar Fundamental Analysis
The Dollar Index is holding near 101.83.
The dollar strengthened slightly against the euro in early trading as political unrest in France added pressure to the single currency.
The dollar is currently caught between two opposing forces.
USD Bullish Drivers
- persistent US inflation;
- stronger US growth than many developed economies;
- high absolute interest rates;
- European political uncertainty;
- potential December Fed tightening.
USD Bearish Drivers
- falling Treasury yields;
- lower oil prices;
- reduced October Fed-hike expectations;
- AI-related financial stress.
This means the US dollar is no longer receiving automatic support from stronger inflation data.
Treasury yields have become the more important driver.
US Dollar Fundamental Bias
Neutral
A sustainable return to a bullish USD trend likely requires US Treasury yields to rise again.
EUR/USD Fundamental Analysis
EUR/USD slipped toward approximately 1.1225 during Monday trading.
The euro is under renewed pressure from political instability in France.
Violent protests related to the cost of living have increased uncertainty around French fiscal and political conditions.
EUR/USD Bullish Drivers
EUR/USD could strengthen if:
- US Treasury yields continue falling;
- DXY breaks lower;
- French political tensions ease.
EUR/USD Bearish Drivers
The pair could decline if:
- French bond spreads widen;
- political instability intensifies;
- US Treasury yields rebound.
EUR/USD Fundamental Bias
Neutral to Mildly Bearish
The weaker dollar offers support, but French political risk limits the upside.
GBP/USD Fundamental Analysis
Sterling remains primarily dependent on US dollar direction.
Lower Treasury yields are supportive for GBP/USD.
However, the United Kingdom continues to face high borrowing costs and inflation risks from elevated global energy prices.
GBP/USD Fundamental Bias
Neutral to Mildly Bullish
The short-term setup remains constructive while DXY remains below recent highs.
USD/JPY Fundamental Analysis
USD/JPY traded close to 158.00.
The pair remains supported by the large difference between US and Japanese interest rates.
Bank of Japan Governor Kazuo Ueda said inflation is moving closer toward the central bank’s 2% target, keeping attention on future Japanese policy normalization.
USD/JPY Fundamental Bias
Neutral to Mildly Bullish
The major downside risk is another significant fall in US Treasury yields.
Oil Fundamental Analysis Today
Oil is one of today’s biggest market movers.
Brent crude fell approximately 1.5%–1.8%, trading near $108 per barrel.
WTI also declined toward roughly $100.
The decline followed a US decision to ease certain restrictions on Russian energy exports, increasing expectations that more fuel could reach global markets.
Why Oil Is Falling
The market is pricing the possibility of increased Russian diesel and energy supply.
However, there are major uncertainties around:
- implementation;
- export capacity;
- Ukrainian attacks on Russian infrastructure;
- sanctions enforcement.
Middle East supply risks also remain extremely high.
Shipping through the Strait of Hormuz has been severely disrupted.
Physical delivery costs, insurance premiums and tanker rates remain elevated despite lower futures prices.
Oil Bullish Drivers
- Strait of Hormuz disruption
- Middle East shipping attacks
- Iranian tensions
- elevated tanker insurance costs
- infrastructure risk
Oil Bearish Drivers
- easing Russian sanctions
- potential additional Russian exports
- strategic inventory releases
- demand destruction above $100
Oil Fundamental Bias
Neutral to Mildly Bearish Intraday
The short-term price direction is lower, but structural geopolitical risk remains high.
US Treasury Yields Remain a Critical Market Signal
Treasury yields continue to attract enormous attention.
Last week’s AI-related selloff drove investors into government bonds even though US CPI and PPI were stronger than expected.
Monday’s decline in oil has provided another reason for yields to remain under pressure.
For global markets, the relationship remains:
Treasury Yields ↓ → Gold ↑ + Growth Stocks Support + USD Pressure
while:
Treasury Yields ↑ → Gold ↓ + DXY ↑ + Nasdaq Pressure
This relationship should remain one of the most important cross-asset signals this week.
AI Earnings Become the Main Equity-Market Test
The focus now shifts toward corporate earnings.
Meta, Tesla and major semiconductor companies are expected to provide investors with crucial information about whether enormous AI capital expenditure can produce adequate profits.
Analysts expect S&P 500 third-quarter earnings growth of more than 30%, driven heavily by technology.
But investors are becoming increasingly skeptical.
The market wants to know:
How much are companies spending?
How quickly is AI revenue growing?
How much debt is required?
What return is being generated on AI capital expenditure?
These questions could determine whether the recent technology correction continues or reverses.
Nasdaq Fundamental Outlook
Nasdaq futures were around 1.3% higher during Monday’s session.
Lower Treasury yields are supportive for high-duration technology stocks.
However, AI financing concerns remain unresolved.
The Philadelphia Semiconductor Index recently recorded its longest losing streak since 2008.
Nasdaq Bullish Scenario
Technology stocks could recover if:
- Meta and Tesla beat expectations;
- AI guidance remains strong;
- Treasury yields remain lower;
- semiconductor earnings exceed forecasts.
Nasdaq Bearish Scenario
Another correction could develop if:
- AI capital expenditure rises sharply;
- earnings guidance disappoints;
- credit spreads widen;
- Treasury yields rebound.
Nasdaq Fundamental Bias
Neutral to Mildly Bullish
Lower yields support valuations, but earnings risk is unusually high.
S&P 500 Fundamental Outlook
S&P 500 futures rose approximately 0.8% during Monday trading.
The decline in oil and Treasury yields is helping risk sentiment.
However, the index remains highly dependent on corporate earnings.
Technology companies now represent a significant share of expected earnings growth.
S&P 500 Fundamental Bias
Neutral to Mildly Bullish
Strong earnings could stabilize the market after last week’s correction.
Today’s Key Economic Events — October 19, 2026
The Daily Fundamental Analysis October 19 2026 includes today’s already released Chinese economic data and the main upcoming US release.
All times are GMT / UTC.
| Time GMT | Currency | Event | Actual | Forecast | Previous |
|---|---|---|---|---|---|
| Released | CNY | Q3 GDP YoY | 4.5% | 4.4% | 4.3% |
| Released | CNY | Industrial Production YoY | 5.5% | 5.4% | 5.2% |
| Released | CNY | Retail Sales YoY | 1.1% | 0.5% | 0.4% |
| Released | CNY | New Home Prices MoM | -0.1% | — | — |
| 14:00 | USD | NAHB Housing Market Index | Pending | 31 | 32 |
| 15:30 | USD | 3-Month Treasury Bill Auction | Pending | — | 4.085% |
| 15:30 | USD | 6-Month Treasury Bill Auction | Pending | — | 4.200% |
The NAHB Housing Market Index is expected to decline to 31 from 32, indicating continued weakness in US home-builder sentiment.
US Housing Market: NAHB Index in Focus
The NAHB Housing Market Index is today’s main scheduled US economic release.
The index is expected at:
Forecast: 31
Previous: 32
Any reading below 50 indicates that more builders view conditions as poor than good.
US housing remains under pressure from:
- high mortgage rates;
- high construction costs;
- labor shortages;
- weak affordability.
Stronger NAHB Scenario
If the index exceeds expectations:
USD Mildly Positive
Treasury Yields Mildly Higher
Homebuilder Stocks Support
Weaker NAHB Scenario
If the index falls significantly below 31:
Growth Concerns ↑
Treasury Yields ↓
USD Pressure
Gold Support
However, today’s housing data are unlikely to dominate markets unless the surprise is unusually large.
Daily Fundamental Analysis October 19 2026: Market Bias
| Asset | Fundamental Bias | Confidence | Main Driver |
|---|---|---|---|
| Gold / XAUUSD | Mildly Bullish | Moderate | Lower oil + lower yields |
| Silver / XAGUSD | Mildly Bullish | Moderate | Gold + yields |
| DXY | Neutral | Moderate | Inflation vs lower yields |
| EUR/USD | Neutral → Bearish | Moderate | French political risk |
| GBP/USD | Neutral → Bullish | Low | Softer USD |
| USD/JPY | Neutral → Bullish | Moderate | Yield differential |
| AUD/USD | Mildly Bullish | Moderate | Strong China data |
| USD/CAD | Neutral | Low | Oil decline vs Canada weakness |
| S&P 500 | Neutral → Bullish | Moderate | Lower yields + earnings |
| Nasdaq | Neutral → Bullish | Moderate | Lower yields + earnings |
| Brent Oil | Neutral → Bearish | Moderate | Russian supply expectations |
| Copper | Mildly Bullish | Moderate | China industrial data |
| US Treasuries | Mildly Bullish | Moderate | Lower oil + risk demand |
7 Trader Watchpoints for October 19, 2026
1. Gold Above $4,180
Gold is benefiting from lower oil prices and Treasury yields.
A sustained move above recent resistance would strengthen the bullish setup.
2. China GDP at 4.5%
The stronger headline is positive for commodities and regional growth expectations.
However, weak property activity remains an important warning signal.
3. Brent Near $108
The decline in oil is reducing immediate inflation pressure.
A move back above $110 would change that narrative quickly.
4. Dollar Index Near 101.8
DXY remains below recent highs.
The next major directional signal is likely to come from Treasury yields.
5. Meta and Tesla Earnings
These reports will test whether AI and technology valuations remain justified.
6. Semiconductor Results
The semiconductor sector recently experienced one of its longest losing streaks in years.
Strong earnings guidance could trigger a meaningful recovery.
7. US Housing Sentiment
The NAHB Housing Market Index provides another signal on how high interest rates are affecting the US economy.
Scenario Analysis for Today’s Markets
Scenario 1: Oil Continues Falling + Treasury Yields Decline
This would be the most favorable combination for gold and technology stocks.
Potential reaction:
Gold ↑
Nasdaq ↑
DXY ↓
EUR/USD ↑
Scenario 2: Oil Rebounds Above $110
This could reignite inflation concerns.
Potential reaction:
Inflation Expectations ↑
Treasury Yields ↑
USD ↑
Gold Mixed to Lower
Nasdaq ↓
Scenario 3: AI Earnings Expectations Improve
Strong pre-earnings guidance could restore risk appetite.
Potential reaction:
Nasdaq ↑
S&P 500 ↑
Treasury Safe-Haven Demand ↓
Gold Consolidates
Scenario 4: AI Concerns Intensify
If investors become more concerned about capital expenditure and debt:
Nasdaq ↓
Treasuries ↑
Yields ↓
Gold ↑
This remains an important non-traditional bullish scenario for gold.
Final Daily Fundamental Outlook
The Daily Fundamental Analysis October 19 2026 shows global markets starting the new week with a more constructive environment for gold and equities, but significant underlying risks remain.
China’s GDP exceeded expectations.
Industrial production accelerated.
Retail sales improved.
These developments provide some support for global growth expectations and commodity demand.
However, China’s property sector remains deeply weak.
This limits the strength of the bullish China narrative.
Gold is benefiting from a combination of lower oil prices and falling Treasury yields.
The US dollar remains near 101.8 and has not regained the momentum seen earlier in October.
Oil is retreating because expectations for higher Russian fuel exports are offsetting part of the Middle East risk premium.
But physical shipping conditions around the Strait of Hormuz remain extremely difficult.
This means crude prices could reverse quickly.
For equities, this week’s most important question is no longer macroeconomic data.
It is earnings.
Meta, Tesla and semiconductor companies must demonstrate that massive AI investment can translate into sustainable earnings and cash flow.
For gold, the strongest bullish combination remains:
Oil ↓ + Treasury Yields ↓ + USD ↓
For the dollar:
Treasury Yields ↑ + Fed Expectations ↑
For Nasdaq:
Strong AI Earnings + Lower Treasury Yields
The central market question today is:
Can lower energy prices and strong corporate earnings restore confidence without reigniting Treasury yields?
The answer will determine whether gold can extend its move above $4,180 and whether global equity markets can recover from last week’s AI-driven volatility.
For definitions of GDP, Treasury yields, inflation and other concepts used in this analysis, visit the FastPip Financial Glossary.
Frequently Asked Questions
What Is the Daily Fundamental Analysis October 19 2026 Outlook for Gold?
The Daily Fundamental Analysis October 19 2026 suggests a mildly bullish short-term outlook for gold because oil prices and Treasury yields are declining.
Why Is Gold Rising Today?
Gold is benefiting from softer oil prices, lower Treasury yields and continued uncertainty around global AI investments.
What Was China’s Q3 GDP?
China’s economy expanded 4.5% year-over-year, above the 4.4% forecast and up from 4.3% in Q2.
What Happened to China Retail Sales?
September Retail Sales increased 1.1% year-over-year, beating the 0.5% forecast and improving from 0.4% previously.
What Happened to China Industrial Production?
Industrial production increased 5.5%, above the 5.4% forecast and 5.2% previous reading.
Why Are Oil Prices Falling?
Oil is falling because the market expects easing restrictions on Russian energy exports to increase global supply. Middle East shipping risks remain a major counterweight.
Is the US Dollar Bullish Today?
The US dollar has a neutral fundamental bias. Persistent inflation supports the currency, while lower Treasury yields limit upside potential.
What Is Today’s Main US Economic Event?
The NAHB Housing Market Index at 14:00 GMT is the main scheduled US economic release. The index is forecast at 31 versus 32 previously.
What Is the Biggest Market Risk This Week?
The biggest risk is whether earnings from Meta, Tesla and major semiconductor companies can justify current AI-related investment and valuations.
What Should Traders Watch After the Daily Fundamental Analysis October 19 2026?
Following the Daily Fundamental Analysis October 19 2026, traders should monitor gold above $4,180, China growth data, Brent crude near $108, US Treasury yields, DXY near 101.8, Meta and Tesla earnings, semiconductor results and AI credit-market developments.
 Check Our
 Whether you’re a day trader or a long-term investor, FastPip gives you the tools to trade smarter, not harder.