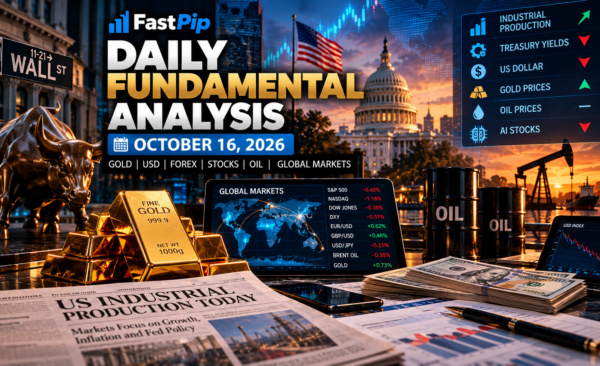
Weekly Fundamental Analysis October 12–16 2026 | FastPip
Weekly Fundamental Analysis October 12–16 2026: 7 Critical Market Signals
The Weekly Fundamental Analysis October 12–16 2026 captures one of the most complex macro trading weeks of recent months.
US inflation accelerated more than expected.
Producer prices posted their largest monthly increase in more than four years.
Retail sales remained stronger than forecast.
Oil returned toward $110 per barrel.
Yet US Treasury yields fell, the dollar recorded its first weekly decline in more than a month, and gold remained above $4,100.
At the same time, one of the strongest themes of 2026 — artificial intelligence — experienced a major confidence shock.
Investors began questioning whether highly leveraged AI infrastructure companies can generate returns quickly enough to justify enormous capital expenditure and debt burdens.
The result was an unusual cross-asset environment:
Inflation ↑
but also:
Treasury Demand ↑ → Yields ↓
This divergence became the defining market signal of the week.
For traders, seven major themes dominated:
- US CPI accelerated to 3.7%
- US PPI surged 1.3% in one month
- Treasury yields fell despite inflation
- The US dollar recorded a weekly decline
- Gold remained resilient above $4,100
- AI and semiconductor stocks sold off sharply
- Oil approached $110 as geopolitical supply risk intensified
For upcoming economic events, traders can monitor the FastPip Economic Calendar.
Weekly Fundamental Analysis October 12–16 2026: Market Performance
| Asset / Market | Weekly Direction | Main Driver |
|---|---|---|
| Gold / XAUUSD | Mildly Bearish | Hot inflation vs lower yields |
| US Dollar / DXY | Bearish | Falling Treasury yields |
| EUR/USD | Mildly Bullish | USD correction |
| GBP/USD | Bullish | Weaker dollar |
| USD/JPY | Mildly Bearish | Lower US yields |
| USD/CAD | Mixed | Weak Canada vs high oil |
| S&P 500 | Bearish | AI concerns + inflation |
| Nasdaq | Strongly Bearish | AI and semiconductor selloff |
| US Treasuries | Bullish | Safe-haven demand |
| Brent Oil | Bullish | Middle East supply risk |
| WTI Oil | Bullish | Hormuz + Russia supply concerns |
Monday: Markets Position for US Inflation
The week began with traders preparing for Wednesday’s US CPI report.
Gold initially reached a one-week high before losing momentum as the dollar and oil strengthened.
Spot gold finished Monday around $4,169 per ounce.
The key macro concern was simple:
High energy prices were threatening to push inflation higher again.
That raised the risk of additional Federal Reserve tightening.
Reuters reported that gold ended Monday lower as traders positioned ahead of US inflation data while oil and the dollar remained firm.
This created the central gold conflict that would remain throughout the week:
Inflation Risk → Higher Rates → Gold Negative
versus:
Financial Stress + Geopolitics → Safe-Haven Demand → Gold Positive
Wednesday: US CPI Reignites Rate-Hike Fears
Wednesday delivered the week’s first major shock.
September US consumer inflation accelerated beyond expectations.
US CPI Results
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Headline CPI MoM | 0.6% | 0.6% | 0.4% |
| Headline CPI YoY | 3.7% | 3.6% | 3.4% |
| Core CPI MoM | 0.3% | 0.2% | 0.3% |
| Core CPI YoY | 2.6% | 2.5% | 2.4% |
Both headline and core annual inflation exceeded expectations.
Gasoline was a major contributor.
But the more important concern was that underlying inflation also remained persistent.
That challenged the idea that the Federal Reserve could quickly move toward easier policy.
Reuters reported that the hotter CPI reading sharply increased debate over whether another Federal Reserve rate increase could be required.
Immediate Market Reaction
The initial reaction followed the traditional macro playbook:
Inflation ↑
Dollar ↑
Treasury Yields ↑
Gold ↓
Technology Stocks ↓
The Nasdaq closed sharply lower as high-growth AI stocks reacted negatively to renewed interest-rate risk.
But that relationship did not survive for long.
Thursday: PPI Produces an Even Bigger Inflation Shock
Thursday brought another major inflation surprise.
US producer prices increased 1.3% month-over-month, compared with expectations of roughly 0.5%.
Annual PPI reached 6.3%.
This was the largest monthly increase in approximately four and a half years.
US PPI Results
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| PPI MoM | 1.3% | 0.5% | 0.5% revised |
| PPI YoY | 6.3% | — | 5.6% |
| Energy Prices | +10.8% | — | — |
| Gasoline Prices | +20.3% | — | — |
| Services Prices | +0.8% | — | +0.2% |
Energy was a major contributor.
However, services inflation also accelerated substantially.
That suggests inflation pressure is broader than simply an oil-price shock.
This matters because several PPI components feed into the Federal Reserve’s preferred PCE inflation measure.
Retail Sales Remained Strong
US Retail Sales increased 0.8% month-over-month, comfortably above the consensus estimate of around 0.3%.
However, the underlying picture was less impressive.
The control-group measure increased only around 0.1%.
Retail Sales Results
| Indicator | Actual | Forecast | Previous |
|---|---|---|---|
| Retail Sales MoM | 0.8% | 0.3% | 1.3% |
| Control Group Sales | 0.1% | — | 1.2% |
Some of the headline strength reflected higher gasoline prices rather than stronger real consumer demand.
The message therefore became more complicated:
Nominal Spending Strong
but:
Underlying Consumption Momentum Slowing
This increased discussion around a possible stagflationary environment.
US Labor Market Remains Low-Hire, Low-Fire
Initial Jobless Claims rose only slightly to 199,000, remaining below 200,000 for a fifth consecutive week.
Continuing claims declined to approximately 1.71 million.
| Labor Indicator | Actual | Previous |
|---|---|---|
| Initial Jobless Claims | 199K | 198K |
| Continuing Claims | 1.710M | 1.714M |
The labor market remains unusual.
Hiring is weak.
But layoffs are also very low.
That has created what economists increasingly describe as a:
Low-Hire, Low-Fire Labor Market
This matters for monetary policy because weak job creation alone may not be enough to justify easier policy while inflation remains elevated.
The Most Important Market Signal: Treasury Yields Fell Anyway
The biggest surprise of the Weekly Fundamental Analysis October 12–16 2026 was not CPI or PPI.
It was the bond market.
Hot inflation should normally push Treasury yields higher.
Instead, investors bought government bonds aggressively during the technology-sector selloff.
The 10-year Treasury yield moved toward 5%, down from roughly 5.3% the previous week.
Why?
Because investors were suddenly worried about the financial risks surrounding the AI investment boom.
Government bonds began behaving like traditional safe-haven assets again.
The relationship changed from:
Inflation ↑ → Bonds ↓
toward:
Equity Risk ↑ → Bonds ↑
This may become one of the most important cross-asset themes heading into the new week.
AI Trade Suffers a Major Confidence Shock
Technology stocks experienced a difficult week.
Investors began questioning whether the enormous investment required for artificial intelligence infrastructure could generate sufficient returns.
The concern was particularly visible in highly leveraged data-center and cloud-infrastructure companies.
CoreWeave became one of the symbols of this shift.
Its equity and debt came under significant pressure as investors reassessed:
- data-center profitability;
- leverage;
- refinancing costs;
- AI capital expenditure;
- future revenue assumptions.
Reuters reported that concerns over AI infrastructure debt drove investors toward safe-haven government bonds.
Why AI Financing Matters
The AI boom requires massive investment in:
- advanced semiconductors;
- data centers;
- electricity;
- cooling infrastructure;
- networking equipment;
- cloud capacity.
Much of that expansion requires substantial financing.
When interest rates rise:
Capital Costs ↑
and:
Required Investment Returns ↑
If revenue growth fails to justify those costs, equity valuations and credit markets can both come under pressure.
Nasdaq Weekly Analysis
The Nasdaq was one of the week’s biggest losers.
By Friday, it was heading toward a weekly decline of more than 4%.
The Philadelphia Semiconductor Index has also fallen roughly 12% during October, despite remaining strongly positive for the year.
This is an important change.
The technology selloff is no longer simply a valuation correction.
The market is beginning to examine:
Profitability
Debt
and:
Return on AI Capital Expenditure
Nasdaq Weekly Bias
Bearish / High Volatility
A sustainable recovery probably requires both:
Lower Treasury Yields
and:
Strong Earnings from Major AI Companies
S&P 500 Weekly Analysis
The S&P 500 also recorded a difficult week.
Reuters described it as the index’s steepest weekly decline since June, even though the market remains relatively close to record levels.
The Dow performed better and managed a slight weekly gain, highlighting the rotation away from some expensive growth stocks.
S&P 500 Weekly Bias
Neutral to Mildly Bearish
The index remains supported by earnings growth, but expensive valuations and AI concentration create downside risk.
Gold Weekly Fundamental Analysis
Gold experienced significant volatility but remained comparatively resilient.
Spot gold traded around $4,165 per ounce on Friday.
For the full week, bullion declined approximately 0.7%.
That performance is important.
Inflation was hotter than expected.
Normally, that should have produced a larger decline.
But lower Treasury yields and a weaker dollar provided significant support.
Gold Bullish Drivers
- falling Treasury yields;
- softer US dollar;
- AI-related financial stress;
- geopolitical uncertainty;
- high government debt;
- Middle East risk.
Gold Bearish Drivers
- 3.7% US inflation;
- 6.3% producer inflation;
- potential Fed tightening;
- high nominal interest rates;
- oil above $100.
Gold Weekly Bias
Neutral to Mildly Bullish
Gold’s weekly decline was relatively contained given the inflation shock.
That suggests safe-haven demand remains strong.
The most important relationship heading into next week is:
Treasury Yields ↓ + USD ↓ = Gold Support
Traders can compare this macro view with current FastPip Trading Signals.
US Dollar Weekly Fundamental Analysis
The Dollar Index fell to approximately 101.87 on Friday.
It declined roughly 0.35% over the week, marking its first weekly loss in more than a month.
That may appear surprising after CPI and PPI both exceeded expectations.
But lower Treasury yields reduced the dollar’s yield advantage.
The market also reduced expectations for an immediate October Fed hike.
By Friday, markets were assigning roughly an 83% probability that the Fed would hold rates unchanged in October.
USD Bullish Drivers
- persistent inflation;
- relatively strong US economy;
- elevated absolute yields;
- safe-haven demand;
- weak European fundamentals.
USD Bearish Drivers
- lower Treasury yields;
- reduced October hike expectations;
- profit-taking after a strong run;
- AI financial stress.
US Dollar Weekly Bias
Neutral
The medium-term macro case remains relatively supportive.
However, the short-term trend has weakened.
EUR/USD Weekly Fundamental Analysis
EUR/USD benefited from the dollar correction.
The euro gained approximately 0.23% over the week.
This does not mean European fundamentals improved dramatically.
France continues to face fiscal concerns.
European borrowing costs remain elevated.
ECB President Christine Lagarde said this weekend that tighter financial conditions are likely to slow growth and ultimately reduce inflation.
EUR/USD Weekly Bias
Neutral to Mildly Bullish
The euro’s strongest short-term catalyst remains lower US Treasury yields.
GBP/USD Weekly Fundamental Analysis
Sterling also benefited from dollar weakness.
The British pound was among the better-performing major currencies late in the week.
However, UK fiscal uncertainty and high borrowing costs remain important medium-term risks.
GBP/USD Weekly Bias
Mildly Bullish
The short-term setup remains favorable while the dollar stays under pressure.
USD/JPY Weekly Fundamental Analysis
The yen strengthened slightly after four consecutive weekly declines.
Lower Treasury yields reduced the attractiveness of long-dollar carry trades.
However, the US-Japan yield differential remains historically wide.
USD/JPY Weekly Bias
Neutral to Mildly Bearish
A renewed rise in US Treasury yields would quickly challenge this view.
Oil Weekly Fundamental Analysis
Oil ended the week as one of the strongest major asset classes.
Brent reached approximately $109.86 per barrel on Friday.
WTI closed near $101.41.
Both benchmarks were supported by renewed Middle East and Russian supply concerns.
Why Oil Rose
The main drivers included:
- attacks around the Strait of Hormuz;
- declining crude flows through the region;
- threats to Saudi energy infrastructure;
- attacks on Russian refineries;
- uncertainty around Russian diesel supply;
- geopolitical escalation.
Brent briefly approached $110 for the first time since May.
Oil Bullish Drivers
- Hormuz disruption;
- Middle East escalation;
- Saudi infrastructure risk;
- Russian refinery attacks;
- higher freight and insurance costs.
Oil Bearish Drivers
- strategic reserve releases;
- potential sanctions relief;
- demand destruction;
- slower global growth.
Oil Weekly Bias
Bullish / High Volatility
Oil remains one of the biggest threats to the global disinflation narrative.
Weekly Fundamental Analysis October 12–16 2026: Market Bias
| Asset | Bias for Next Week | Main Driver |
|---|---|---|
| Gold / XAUUSD | Neutral → Mildly Bullish | Falling yields + risk aversion |
| US Dollar / DXY | Neutral | Inflation vs lower yields |
| EUR/USD | Neutral → Mildly Bullish | USD correction |
| GBP/USD | Mildly Bullish | Softer USD |
| USD/JPY | Neutral → Mildly Bearish | Lower yields |
| USD/CAD | Neutral | Oil vs Canadian weakness |
| S&P 500 | Neutral → Bearish | Earnings + AI concerns |
| Nasdaq | Bearish / Volatile | AI profitability concerns |
| Brent Oil | Bullish | Geopolitical supply risk |
| WTI Oil | Bullish | Tight supply |
| US Treasuries | Neutral → Bullish | Safe-haven demand |
7 Key Lessons From the Week
1. Inflation Is Clearly Not Defeated
Both CPI and PPI exceeded expectations.
The inflation story has therefore become more difficult for the Federal Reserve.
2. Bond Markets Changed Behavior
Treasury prices rose even though inflation accelerated.
This suggests bonds may once again be acting as a genuine hedge against equity-market risk.
3. AI Is Becoming a Financial-Risk Story
The market is no longer evaluating AI only through revenue growth.
Debt, interest costs and return on capital are becoming equally important.
4. Gold Survived an Extremely Difficult Macro Week
A weekly decline of around 0.7% was relatively limited considering the size of the inflation surprises.
That suggests underlying demand remains resilient.
5. The Dollar Needs Higher Yields
Hot inflation alone was not enough to keep DXY rising.
The dollar’s next major move may depend more on bond-market behavior than individual inflation releases.
6. Oil Is Still a Global Inflation Threat
Brent near $110 can materially affect inflation expectations worldwide.
7. Fed Policy Is Becoming More Complicated
The Federal Reserve is balancing:
High Inflation
against:
Financial-Market Stress
and:
Slower Hiring
That makes future policy increasingly difficult to predict.
What Traders Should Watch Next Week
The week of October 19–23, 2026 will shift some attention away from macroeconomic data and toward corporate earnings.
The biggest question will be whether major technology companies can restore confidence in the AI investment cycle.
Reuters reports that investors will closely watch major earnings including Meta Platforms, Tesla, Lam Research, Texas Instruments, Netflix, Procter & Gamble and GE Aerospace.
Meta and AI Capital Spending
Meta will be particularly important.
Investors want evidence that massive investment in AI data centers can generate sufficient returns.
If management increases capital spending without demonstrating stronger profitability, AI-related stocks could face renewed pressure.
Semiconductor Earnings
Lam Research and Texas Instruments will provide insight into global chip demand.
Semiconductor stocks have been one of the weakest areas of the market in October.
Strong earnings could stabilize sentiment.
Weak guidance could extend the correction.
Tesla
Tesla remains another important sentiment indicator.
Its results will influence both growth-stock confidence and expectations around capital expenditure.
China GDP Is Another Major Risk
China is expected to report third-quarter economic growth next week.
A Reuters poll indicates Q3 GDP growth around 4.4% year-over-year, slightly higher than 4.3% in Q2.
However, China’s economy still faces:
- weak consumer demand;
- property-sector weakness;
- sluggish private investment;
- trade tensions.
Strong China GDP Scenario
Potential reaction:
Copper ↑
AUD ↑
Asian Equities ↑
Commodity Demand ↑
Weak China GDP Scenario
Potential reaction:
Copper ↓
AUD ↓
USD Safe-Haven Demand ↑
Global Growth Concerns ↑
Next Week Scenario Analysis
Scenario 1: Strong Tech Earnings + Stable Treasury Yields
This would be the most constructive environment for equities.
Potential reaction:
Nasdaq ↑
S&P 500 ↑
Gold Neutral
USD Mixed
Scenario 2: Weak AI Earnings + Falling Treasury Yields
This would reinforce risk aversion.
Potential reaction:
Treasuries ↑
Gold ↑
Nasdaq ↓
USD Mixed
Gold could outperform because falling yields would reduce its opportunity cost.
Scenario 3: Oil Breaks Above $110
A sustained Brent move above $110 could reignite inflation fears.
Potential reaction:
Inflation Expectations ↑
Fed-Hike Risk ↑
Gold Initially Mixed
USD ↑
Growth Stocks ↓
Scenario 4: Oil Falls and AI Earnings Improve
This may be the best risk-asset combination.
Inflation Pressure ↓ + Earnings Confidence ↑
Potential reaction:
S&P 500 ↑
Nasdaq ↑
Treasury Yields Stable
Gold Consolidates
Final Weekly Fundamental Outlook
The Weekly Fundamental Analysis October 12–16 2026 reveals an important change in the way global markets are responding to macroeconomic risk.
Inflation accelerated significantly.
US CPI reached 3.7%.
Producer prices jumped 1.3% in one month.
Oil approached $110 per barrel.
Under normal circumstances, this combination would produce significantly higher Treasury yields and a stronger US dollar.
Instead, Treasury yields declined.
The dollar recorded its first weekly loss in more than a month.
Gold remained above $4,100.
The explanation lies in the rapid reassessment of the artificial-intelligence investment boom.
Concerns about debt, capital expenditure and profitability pushed investors toward safe-haven government bonds.
That change has created a new market regime.
For gold, this environment is potentially constructive.
High inflation remains negative because it supports higher interest rates.
But financial stress and declining Treasury yields provide important support.
For the dollar, inflation alone may no longer be sufficient.
DXY probably needs Treasury yields to rise again to restart its broader rally.
For equities, next week’s earnings season becomes critical.
The market needs evidence that AI-related capital expenditure can generate real earnings and cash flow.
For oil, geopolitical conditions remain the central variable.
A sustained move above $110 could materially increase global inflation expectations and alter central-bank policy assumptions again.
The key cross-asset relationships for next week are:
AI Stress ↑ → Treasury Demand ↑ → Yields ↓ → Gold Support
and:
Oil ↑ → Inflation ↑ → Fed Risk ↑ → Growth Stocks Pressure
The market may therefore remain caught between two competing forces:
Financial Risk
and:
Inflation Risk
Whichever dominates will likely determine the next major move in gold, the dollar, bonds and global equity indices.
For definitions of CPI, PPI, Treasury yields, inflation and other market terminology used in this analysis, visit the FastPip Financial Glossary.
Frequently Asked Questions
What Does the Weekly Fundamental Analysis October 12–16 2026 Suggest for Gold?
The Weekly Fundamental Analysis October 12–16 2026 suggests a neutral-to-mildly bullish outlook for gold.
Falling Treasury yields and financial-market uncertainty support bullion, while high inflation remains the main downside risk.
Did Gold Rise or Fall Last Week?
Gold declined approximately 0.7% during the week and traded around $4,165 per ounce on Friday.
Why Did the US Dollar Fall Despite High Inflation?
The dollar weakened because Treasury yields declined as investors moved into government bonds during the AI-related equity selloff.
DXY ended Friday near 101.87 and lost around 0.35% for the week.
What Happened to US Inflation?
Headline CPI accelerated to 3.7% year-over-year, while core CPI increased to 2.6%.
Producer prices also surged, with PPI increasing 1.3% month-over-month.
Why Did Technology Stocks Fall?
Investors became increasingly concerned about AI infrastructure costs, debt levels, semiconductor valuations and whether future earnings can justify current capital expenditure.
What Happened to the Nasdaq?
The Nasdaq was heading toward a weekly decline of more than 4%, with AI-related and semiconductor companies among the biggest losers.
Why Did Oil Rise?
Oil rose because of renewed fears over Middle East supply disruptions, the Strait of Hormuz, Saudi infrastructure risks and attacks on Russian energy facilities.
Brent reached almost $110 per barrel on Friday.
Is the Federal Reserve Likely to Raise Rates in October?
By Friday, markets were assigning approximately an 83% probability that the Fed would leave rates unchanged in October, despite stronger inflation data.
What Is the Biggest Market Risk Next Week?
The biggest risk is whether earnings from major AI and technology companies can restore confidence after the recent selloff.
Oil prices and Treasury yields are also critical.
What Should Traders Watch After the Weekly Fundamental Analysis October 12–16 2026?
Following the Weekly Fundamental Analysis October 12–16 2026, traders should monitor Meta and Tesla earnings, semiconductor results, China GDP, US Treasury yields, the Dollar Index, gold above $4,100, Brent crude near $110 and developments in AI credit markets.
 Check Our
 Whether you’re a day trader or a long-term investor, FastPip gives you the tools to trade smarter, not harder.