How to Allocate Capital Between Signal Services: A Risk Management Guide
How to Allocate Capital Between Signal Services: A Risk Management Guide
Following more than one trading signal provider can reduce dependence on a single strategy, but only when capital is allocated correctly.
Simply subscribing to three or four signal services does not automatically create diversification.
If all of them trade the same instruments, use similar strategies, enter positions in the same direction, or take comparable risks, your account may still be heavily concentrated.
That is why traders who allocate capital between signal services need to think beyond percentages.
The real objective is to build a structure where:
- No single provider can dominate total account risk
- Different strategies contribute genuinely different exposures
- Drawdown remains manageable
- Capital allocation can be reviewed objectively
- Performance is measured using actual data
- Correlated positions are controlled
The underlying principle is similar to portfolio diversification.
Investor.gov describes diversification as spreading money across different investments to reduce risk and also notes that simply owning several investments does not necessarily mean a portfolio is truly diversified if those holdings are too similar.
Investor.gov – Asset Allocation and Diversification
The same principle can be applied conceptually to signal providers.
The objective is not to follow as many services as possible.
It is to combine a limited number of sufficiently different services within a controlled risk framework.
Why Traders Use Multiple Signal Services
The primary reason is diversification.
Every trading system has strengths and weaknesses.
A trend-following service may perform well during strong directional markets but struggle during sideways conditions.
A mean-reversion strategy may perform well during range-bound markets but experience difficulty when a powerful trend develops.
A scalping service may focus on very short-term movements, while another provider may hold positions for several days.
By combining genuinely different strategies, traders may reduce their dependence on one specific market environment.
But this works only when the providers are meaningfully different.
Diversification Is Not About the Number of Providers
Suppose you follow four signal services.
At first glance, that sounds diversified.
But imagine all four:
- Trade Gold
- Use 15-minute charts
- Trade breakout strategies
- Enter after US economic news
- Use similar Stop Loss distances
You do not really have four independent risk sources.
You may effectively have one large Gold breakout strategy divided across four providers.
That is false diversification.
True diversification requires differences in factors such as:
- Instruments
- Markets
- Timeframes
- Strategy logic
- Holding periods
- Risk structure
- Market regime exposure
FastPip’s guide to different trading styles shows how scalping, day trading, swing trading and position trading differ substantially in holding period, execution requirements and risk characteristics.
Benefits of Allocating Capital Between Multiple Signal Services
A structured allocation can offer several advantages.
Reduced Provider Concentration
If 100% of trading capital depends on one provider, deterioration in that provider’s performance affects the entire allocation.
Using several carefully selected services can reduce this dependency.
Exposure to Different Strategies
Different strategies may perform differently across market regimes.
A diversified combination may include:
- Trend following
- Mean reversion
- Intraday trading
- Swing trading
- Fundamental trading
The goal is not to maximize the number of trades.
The goal is to avoid depending entirely on one trading logic.
Smoother Portfolio-Level Results
Suppose Provider A enters a difficult period while Provider B continues performing near its historical range.
Provider B may partially offset the weakness of Provider A.
This does not eliminate losses.
It can simply reduce the impact of one provider on the total portfolio.
Investor.gov similarly explains that diversification may help reduce portfolio risk because different investments can react differently to market conditions.
Better Provider Evaluation
Allocating capital across several providers also makes direct comparison possible.
You can evaluate:
- Net return
- Maximum Drawdown
- Win rate
- Average win
- Average loss
- Risk-to-reward
- Consistency
- Actual execution quality
This is much more useful than relying only on marketing statistics.
Risks of Using Multiple Signal Services
More providers can also create more problems.
Increased Complexity
Each service generates:
- Signals
- Updates
- Stop Loss changes
- Take Profit changes
- Performance data
Managing several providers can become difficult quickly.
Conflicting Signals
Provider A may issue:
XAUUSD BUY
while Provider B issues:
XAUUSD SELL
Without predefined rules, traders may become confused or make emotional decisions.
Duplicate Risk
An even more dangerous situation occurs when several providers issue the same trade.
For example:
Provider A: XAUUSD BUY
Provider B: XAUUSD BUY
Provider C: XAUUSD BUY
If each position risks 1% of the account, total Gold exposure may effectively become:
3%
The trader may think they are diversified across three providers.
In reality, all three trades depend heavily on the same market move.
Should Every Signal Provider Receive an Equal Allocation?
Not necessarily.
Equal allocation is simple, but simplicity does not mean optimality.
Providers can differ in:
- Historical performance
- Maximum Drawdown
- Volatility
- Track record
- Risk per trade
- Strategy type
- Transparency
- Reliability
Allocating identical amounts to a conservative five-year track record and a newly launched aggressive strategy may not reflect their different risk characteristics.
However, equal allocation can still be useful as a starting framework.
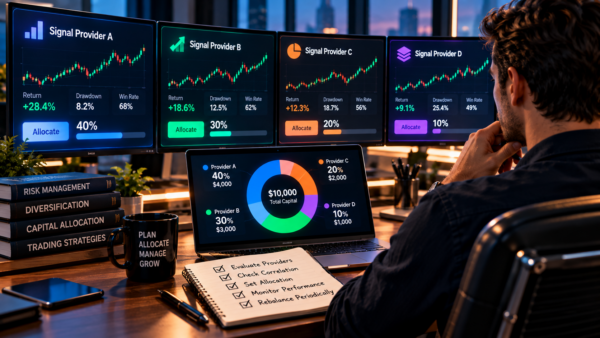
Method 1: Equal Capital Allocation
This is the simplest way to allocate capital between signal services.
Suppose total trading capital is:
$10,000
You follow four providers.
An equal allocation would be:
| Signal Service | Allocation | Capital |
|---|---|---|
| Service A | 25% | $2,500 |
| Service B | 25% | $2,500 |
| Service C | 25% | $2,500 |
| Service D | 25% | $2,500 |
This structure is easy to understand and monitor.
Advantages of Equal Allocation
It:
- Reduces subjective decisions
- Prevents immediate overconfidence in one provider
- Creates a simple testing framework
- Makes performance comparison easier
For new providers, this can be particularly useful during an evaluation phase.
Limitations of Equal Allocation
The main problem is that it assumes every provider deserves the same weight.
That may be unrealistic.
Service A may have:
- Five years of history
- Moderate drawdown
- Stable risk
Service D may have:
- Three months of history
- High drawdown
- Aggressive leverage
Giving both identical capital does not necessarily produce equal risk.
Method 2: Performance-Based Allocation
A more advanced approach is to allocate more capital to providers demonstrating stronger risk-adjusted performance.
Potential factors include:
- Long-term return
- Maximum Drawdown
- Return consistency
- Average risk per trade
- Risk-to-reward
- Number of trades
- Track record length
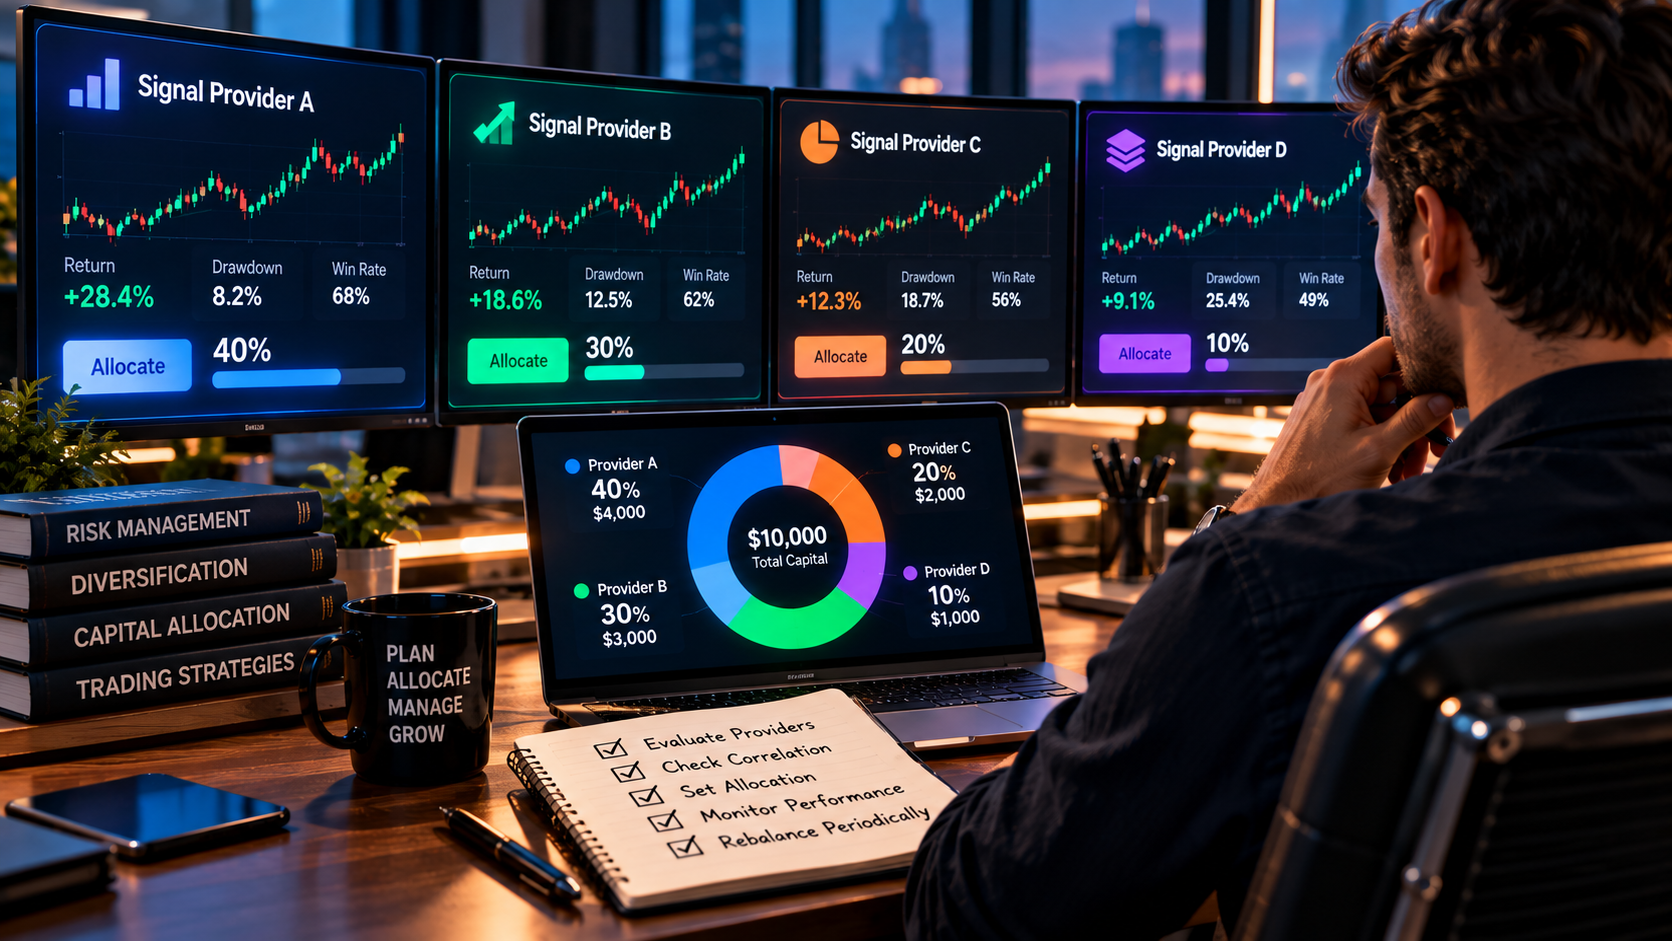
For example:
| Provider | Weight |
|---|---|
| Service A | 40% |
| Service B | 30% |
| Service C | 20% |
| Service D | 10% |
This example is illustrative rather than a recommendation.
The idea is simply that all providers do not need identical weights.
Do Not Allocate Based Only on Profit
Suppose:
Provider A
Return: 50%
Maximum Drawdown: 12%
Provider B
Return: 80%
Maximum Drawdown: 55%
Provider B made more money.
But it also exposed capital to substantially greater historical risk.
Allocating capital purely according to return could therefore unintentionally increase overall portfolio risk.
Method 3: Risk-Based Allocation
Instead of asking:
Which provider made the most money?
ask:
Which provider contributes the most risk?
Suppose:
Service A
Maximum Drawdown: 8%
Service B
Maximum Drawdown: 15%
Service C
Maximum Drawdown: 35%
You may decide that the aggressive provider should receive less capital.
This helps prevent one high-risk strategy from dominating total account risk.
Method 4: Core and Satellite Allocation
A useful professional framework is a Core & Satellite structure.
The portfolio contains:
Core Providers
More established services with:
- Longer track records
- Better transparency
- Controlled drawdown
- More stable risk
Satellite Providers
Smaller allocations used for:
- New strategies
- Higher-risk opportunities
- Experimental services
- Additional diversification
For example:
Core Service A: 40%
Core Service B: 30%
Satellite Service C: 15%
Satellite Service D: 10%
Cash Reserve: 5%
Again, these percentages are illustrative.
The important concept is that the most trusted strategies form the foundation while less-established services receive limited exposure.
Correlation Is Critical When You Allocate Capital Between Signal Services
Correlation describes the degree to which strategies behave similarly.
You do not need advanced quantitative software to understand the basic concept.
Suppose three providers repeatedly:
- Trade XAUUSD
- Trade in the same direction
- Enter around the same US session
- Respond similarly to CPI and NFP
Their results may be highly related.
If Gold suddenly moves sharply against them, all three can lose simultaneously.
That creates portfolio-level concentration.
Look Beyond Provider Names
Provider diversification is not the same as strategy diversification.
Five different Telegram channels do not necessarily mean five independent strategies.
Evaluate:
- Instruments
- Entry timing
- Trade direction
- Holding period
- Strategy type
If the trades continually overlap, diversification may be weaker than it appears.
Example of Real vs. False Diversification
Portfolio A
Provider 1: Gold Scalping
Provider 2: Gold Intraday
Provider 3: Gold Breakouts
Three providers.
But most risk remains connected to Gold.
Portfolio B
Provider 1: Forex Swing Trading
Provider 2: Index Intraday Trading
Provider 3: Gold Macro Trading
This structure may provide more meaningful diversification because the market exposures and strategy horizons differ.
It still does not guarantee lower losses, but the sources of risk are more distinct.
Set a Maximum Risk for Each Provider
Capital allocation alone is not sufficient.
You should also define maximum acceptable risk.
For example:
Maximum allocation per provider
and separately:
Maximum portfolio risk from simultaneous open trades
These are different controls.
A provider with 25% of your allocated capital should not necessarily be allowed to expose that entire amount to one trade.
Think in Risk Percentages, Not Only Dollars
Suppose:
Provider A receives $3,000.
Provider B receives $3,000.
But:
Provider A risks 0.5% per trade.
Provider B risks 5% per trade.
Capital allocation is identical.
Risk exposure is not.
This is why professional allocation should evaluate both:
Capital Weight + Risk Intensity
Control Combined Exposure
Imagine three providers each risk 1% on EURUSD BUY positions.
If you execute all three signals independently, portfolio risk may become roughly:
3% on essentially the same market thesis
This is a portfolio-level risk-management problem.
A better framework should define a limit for:
- One symbol
- One currency
- One market
- One direction
- Highly correlated trades
This prevents hidden concentration.
Do Not Over-Diversify
More providers are not always better.
At some point, additional services create:
- More subscriptions
- More signals
- More monitoring
- More conflicting trades
- More execution complexity
- More difficulty measuring performance
The goal should be:
Enough diversification to reduce concentration without making the system unmanageable.
For many traders, a small number of well-understood services may be more practical than ten poorly monitored providers.
Track Every Provider Separately
If you use multiple providers, maintain separate performance records.
For each provider, record:
- Capital allocation
- Number of trades
- Net profit/loss
- Maximum Drawdown
- Average win
- Average loss
- Risk per trade
- Trading costs
- Execution differences
Then calculate each service’s contribution to overall portfolio results.
Without separate records, weak providers can remain hidden inside aggregate account performance.
Build a Signal Provider Scorecard
You can also score providers using several categories.
For example:
| Category | Weight |
|---|---|
| Risk Management | 25% |
| Drawdown | 20% |
| Long-Term Performance | 20% |
| Consistency | 15% |
| Transparency | 10% |
| Strategy Diversification | 10% |
The exact weights can vary.
The objective is to avoid making allocation decisions based on one metric such as monthly return.
Keep a Trading Journal
Your own performance data matters more than promotional statistics.
Record:
- Provider
- Signal
- Entry
- Stop Loss
- Target
- Actual execution
- Result
- Risk
- Notes
This allows you to compare:
Provider Reported Performance
with:
Your Real Performance
and determine whether execution differences are materially affecting results.
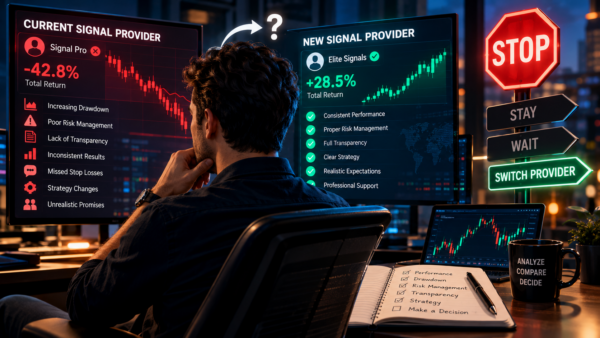
Rebalancing Your Signal Service Allocation
Allocations should not necessarily remain unchanged forever.
Suppose the initial structure is:
Service A: 40%
Service B: 30%
Service C: 20%
Service D: 10%
Over time, performance and risk can change.
A periodic review can determine whether the original allocation remains appropriate.
Investor.gov explains that portfolio allocations can drift as investments perform differently and that rebalancing can be used to restore an intended risk structure.
The same general principle can be applied conceptually to a multi-provider signal portfolio.
Do Not Rebalance After Every Winning or Losing Trade
This is important.
Suppose Service A wins three trades.
Increasing its allocation immediately can create performance chasing.
Then Service B loses three trades.
Reducing it immediately may lock in a short-term emotional response.
Instead, establish a review schedule.
For example:
- Monthly monitoring
- Quarterly allocation review
- Immediate review only after serious risk violations
The exact schedule depends on trading frequency.
When Should Allocation Change?
Consider reviewing weights when:
Drawdown Changes Materially
A provider moves significantly outside historical drawdown ranges.
Risk Behavior Changes
Position sizes or leverage increase.
Strategy Changes
The service begins trading different markets or methods.
Performance Deteriorates Persistently
Not three losing trades—persistent deterioration across a meaningful sample.
Correlation Increases
Two previously independent providers begin producing almost identical trades.
Your Risk Objectives Change
Your personal objectives may become more conservative or aggressive.
Avoid Performance Chasing
One of the biggest allocation mistakes is:
Increasing allocation because a provider just performed exceptionally well.
Past performance does not guarantee future results.
Investor.gov specifically cautions against chasing short-term returns and notes that periodic approaches can help investors avoid some behavioral mistakes associated with buying after strong performance and selling after declines.
This is highly relevant when allocating between signal services.
Do not automatically reward the provider that had the best previous month.
Common Capital Allocation Mistakes
Giving the Best Recent Performer the Most Capital
Short-term performance may contain a large luck component.
Ignoring Drawdown
Profit without risk context is incomplete.
Using Too Many Providers
Complexity can overwhelm the benefits of diversification.
Ignoring Correlation
Different provider names can hide identical market exposure.
Changing Allocations Constantly
Frequent changes can become performance chasing.
Trusting New Providers Too Quickly
A short track record provides limited evidence.
Ignoring Trading Costs
Multiple services can increase:
- Subscription costs
- Spreads
- Commissions
- Execution costs
A Practical Capital Allocation Framework
A simple professional framework can use five steps.
Step 1: Define Total Signal Capital
Decide how much capital belongs to the signal strategy as a whole.
Do not begin with individual providers.
Step 2: Evaluate Each Provider
Assess:
- Track record
- Drawdown
- Risk management
- Transparency
- Strategy
- Consistency
Step 3: Measure Diversification
Ask:
Does this provider add something genuinely different?
If not, it may not deserve additional allocation.
Step 4: Set Provider Weights
Use:
- Equal weighting
- Risk weighting
- Performance weighting
- Core & Satellite
- A combination
Step 5: Set Portfolio Risk Limits
Define maximum acceptable exposure across all providers.
This final step is essential.
Without portfolio-level limits, individually sensible strategies can combine into excessive total risk.
Example: $10,000 Across Four Signal Services
Consider a hypothetical account with:
Total signal capital: $10,000
After evaluating four providers:
Service A
Long history
Low Drawdown
Moderate returns
Service B
Good history
Moderate risk
Strong consistency
Service C
Higher return
Higher Drawdown
Service D
New provider
Limited history
An illustrative allocation could be:
| Service | Allocation | Capital |
|---|---|---|
| A | 40% | $4,000 |
| B | 30% | $3,000 |
| C | 20% | $2,000 |
| D | 10% | $1,000 |
Why?
Not because A necessarily makes the most money.
Because allocation can reflect:
Confidence + Risk + Track Record + Diversification
rather than return alone.
Example: A Poor Allocation
Now imagine:
Service A: 25% – Gold Scalping
Service B: 25% – Gold Scalping
Service C: 25% – Gold Breakouts
Service D: 25% – Gold News Trading
On paper:
Four providers.
In reality:
Almost the entire portfolio depends heavily on Gold.
This is concentration disguised as diversification.
Use FastPip Resources to Understand Strategy Differences
Before combining multiple signal services, traders should understand how different trading styles behave.
Scalping, day trading, swing trading and position trading differ in:
- Trade frequency
- Holding period
- Execution sensitivity
- Transaction costs
- Typical risk structure
FastPip explains these distinctions in its Trading Types guide.
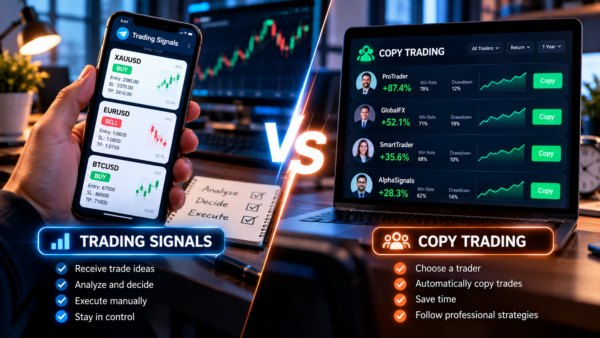
FastPip’s main platform also covers market analysis, signals and copy-trading resources that can help users compare different approaches.
FastPip Trading Signals & Market Analysis
Professional Checklist Before You Allocate Capital Between Signal Services
Before assigning capital, check each provider.
1. Track Record
Is the history long enough?
2. Maximum Drawdown
How much historical capital decline occurred?
3. Risk Per Trade
How aggressively does the provider trade?
4. Strategy Type
Trend following, scalping, swing, news trading?
5. Market Exposure
Forex, Gold, indices, crypto?
6. Correlation
Does it duplicate another provider?
7. Transparency
Are wins and losses both reported?
8. Execution Requirements
Does the strategy require extremely fast fills?
9. Trading Costs
What are the real subscription and execution costs?
10. Role in the Portfolio
Why are you adding this provider?
The final question is especially important.
If you cannot explain what a provider adds to the portfolio, there may be little reason to add it.
A Simple Rebalancing Checklist
At each scheduled review, ask:
- Has long-term performance changed?
- Has Drawdown increased?
- Has risk per trade changed?
- Has strategy drift occurred?
- Has correlation with other providers increased?
- Has transparency changed?
- Does the allocation still fit my risk objectives?
Do not change weights simply because one provider had the best month.
Make allocation changes because the underlying data or risk structure changed.
Conclusion: How to Allocate Capital Between Signal Services Properly
There is no universal formula to allocate capital between signal services.
The best structure depends on:
- Your total trading capital
- Risk tolerance
- Provider quality
- Drawdown
- Strategy differences
- Correlation
- Time horizon
- Ability to monitor multiple systems
Equal allocation can be a useful starting point.
Performance-based allocation can become more useful once sufficient data exists.
Risk-based weighting can reduce the impact of aggressive strategies.
Core & Satellite can provide a practical balance between established providers and newer opportunities.
But the most important principle is this:
Diversify risk—not just provider names.
Three different services trading the same strategy on the same instrument may provide far less diversification than two genuinely different trading systems.
Investor.gov’s diversification guidance makes the broader principle clear: spreading capital can reduce concentration risk, but holdings must actually differ enough to provide meaningful diversification.
The strongest approach is therefore to:
Select carefully → Allocate conservatively → Measure independently → Control correlation → Review periodically
And avoid:
Chasing recent performance → Constantly changing weights → Ignoring total portfolio exposure
The objective is not to identify which provider deserves the largest amount of money after its best month.
The objective is to build a portfolio of trading strategies in which no single provider, strategy, or market can unnecessarily dominate overall risk.
That is the foundation of professional capital allocation across multiple signal services.
Frequently Asked Questions
How should I allocate capital between signal services?
Start by assessing each provider’s track record, drawdown, risk, strategy and correlation with other providers. Capital can then be allocated equally or weighted according to risk and quality.
Should every signal service receive the same amount?
Not necessarily. Equal allocation is simple and useful for initial testing, but providers with different risk profiles may justify different weights.
How many signal providers should I follow?
There is no universal ideal number. The objective is to achieve useful diversification without creating unnecessary complexity.
Is using several signal providers safer?
It can reduce dependence on one provider, but only if the services are genuinely different. Highly correlated strategies can still create concentrated risk.
What is false diversification?
False diversification occurs when several providers appear different but use similar strategies, markets or trade directions, causing them to gain and lose simultaneously.
Should the most profitable provider receive the most capital?
Not automatically. Return should be considered together with drawdown, risk per trade, consistency and track-record length.
What is performance-based allocation?
It is a method where provider weights are adjusted according to measured performance and risk rather than being divided equally.
What is risk-based allocation?
Risk-based allocation gives lower weights to strategies that contribute more volatility, drawdown or portfolio exposure and potentially greater weights to more controlled strategies.
What is Core and Satellite allocation?
It places most capital with established core providers while allocating smaller amounts to newer, more specialized or higher-risk services.
How often should signal allocations be reviewed?
The appropriate frequency depends on trading style, but scheduled monthly or quarterly reviews are generally more disciplined than changing weights after every few trades.
Should I increase allocation after a provider has a great month?
Not automatically. Increasing exposure based mainly on recent performance can become performance chasing.
How can I measure correlation between providers?
Start by checking whether they regularly trade the same instruments, directions, timeframes and strategy types. More advanced users can analyze statistical correlation between return histories.
Should I keep cash unallocated?
That depends on the trader’s risk framework. Maintaining unused capital can provide flexibility and reduce total deployed risk, but there is no universal percentage suitable for everyone.
What should I do when several providers give the same signal?
Treat the combined positions as one larger exposure and check total portfolio risk before executing them all.
What is the biggest mistake when using multiple signal services?
Assuming that having several provider names automatically creates diversification. The underlying strategies and market exposures matter much more.